
Blogs
PW Consulting: Dimethyl Carbonate Market to Reach USD 2,896 Million by 2032 with 8.1% CAGR
By pmarketresearch, 2026-09-15
Dimethyl Carbonate Market Outlook 2026–2032: Strategic Imperatives in a High-Growth Specialty Chemical Landscape
The global Dimethyl Carbonate (DMC) market stands at a critical inflection point. As manufacturers, formulators, and supply chain leaders navigate an environment defined by accelerating electrification, tightening environmental regulations, and volatile raw material dynamics, the ability to anticipate structural shifts in demand, pricing, and competitive positioning has never been more consequential. Our newly released market intelligence study provides a rigorous, forward-looking assessment of the DMC industry across the forecast horizon of 2026 through 2032. Designed for executive decision-makers, this report translates historical trajectories, macro-scale projections, and granular competitive intelligence into actionable strategic roadmaps. Rather than offering static snapshots, it equips organizations with the analytical frameworks necessary to allocate capital, secure supply, and position product portfolios ahead of market inflection cycles.
The DMC sector has experienced sustained expansion over the past half-decade, driven by its dual role as a foundational building block in advanced materials and as a high-performance, low-toxicity solvent aligned with modern sustainability mandates. From a base year valuation in 2025, the overall market has advanced to a projected valuation of USD 1,791.63 million in 2026. Looking ahead through the end of the forecast period in 2032, the market is expected to reach USD 2,896.00 million, underpinned by a compound annual growth rate of 8.1%. These figures reflect more than incremental volume gains; they signal a structural reorientation of DMC consumption toward higher-value applications, geographic demand centers, and purity specifications that reward producers capable of scaling with consistency, regulatory compliance, and technical differentiation.
Historical Trajectory and Forecast Architecture (2020–2032)
Understanding where the market is headed requires a clear lens on how it has evolved. The historical period from 2020 to 2025 captures a phase of resilient growth, during which the market moved from a valuation of USD 1,120.00 million in 2020 to USD 1,676.00 million in 2025. This upward trajectory was shaped by expanding polycarbonate synthesis activity, rising adoption of DMC in advanced battery electrolyte formulations, and a broadening pool of industrial and specialty solvent applications. The post-2025 forecast phase reflects a continuation of this momentum, with annual valuations charting a steady ascent through 2032. The compound annual growth rate of 8.1% positions DMC among the more structurally supported specialty chemical segments, where growth is not merely cyclical but anchored in durable end-use demand drivers.
The forecast model is constructed to isolate the pace, direction, and composition of value creation across multiple dimensions. It reconciles baseline macroeconomic assumptions with application-specific consumption patterns, grade-level differentiation, and regional supply-demand balances. Critically, the analysis does not treat the market as a monolith. Instead, it deconstructs growth into the segments that actually matter to commercial strategy: which grades command premium positioning, which applications are expanding fastest in absolute and relative terms, and where regional manufacturing and procurement ecosystems are likely to concentrate or disperse over the next several years.
Market Architecture: Grades, Applications, and Geographies
The DMC market’s growth story is fundamentally segmented. By grade, the landscape is divided among Industrial Grade, Pharmaceutical Grade, and Battery Grade, each serving distinct technical specifications, regulatory requirements, and pricing dynamics. Industrial-grade volumes anchor broad solvent and chemical synthesis usage, while pharmaceutical-grade supplies cater to highly controlled formulation environments that demand stringent purity and auditability. Battery-grade DMC, meanwhile, has emerged as a strategic differentiator, driven by the relentless scaling of lithium-ion electrolyte production and the material requirements of next-generation energy storage systems.
By application, the market draws its revenue composition from three principal demand pillars. Polycarbonate synthesis remains a foundational consumption route, leveraging DMC as a key intermediate in polymer manufacturing. Battery electrolyte applications represent a rapidly scaling demand channel, reflecting the broader electrification trajectory across automotive, consumer electronics, and stationary storage markets. A third application cluster encompasses solvents and reagents, where DMC's favorable toxicological profile and solvent strength continue to drive substitution away from more hazardous alternatives. Each application pathway carries its own throughput characteristics, specification thresholds, and sensitivity to downstream manufacturing cycles, making application-level visibility indispensable for capacity planning and go-to-market strategy.
Geographically, demand is distributed across a diversified set of regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The regional breakdown reflects differing maturity levels, manufacturing footprints, policy environments, and end-use industrial bases. Some regions are characterized by established production infrastructure and mature solvent markets, while others are experiencing accelerated uptake driven by localized manufacturing expansion, energy transition programs, and shifting trade dynamics. Understanding the interplay between regional demand concentration and supply network resilience is central to managing procurement risk and identifying white-space opportunities.
Competitive Landscape and Strategic Positioning
The DMC industry is shaped by a competitive field that spans multinational chemical producers, specialized high-purity material suppliers, and large-scale regional manufacturers. Market concentration remains moderate, with the top three players accounting for approximately 25% of total market value and the top five firms collectively representing around 35%. This level of concentration suggests a market that is neither highly fragmented nor dominated by a handful of incumbents, creating space for differentiated positioning through grade specialization, geographic footprint, technical service, and supply reliability.
Dimethyl Carbonate (DMC) Market
Several key companies illustrate the strategic diversity within the sector. UBE Corporation, headquartered in Tokyo, produces DMC and ethyl methyl carbonate through phosgene and oxidative carbonylation routes, with manufacturing presence that includes a Louisiana facility and operations in Spain and Thailand. Its focus on battery-grade DMC for lithium-ion electrolytes aligns with the growing premiumization of the segment. Lotte Chemical Corporation, based in Seoul, manufactures DMC as a monomer for polycarbonates and specialty chemicals, supplying industrial and battery grades from Korean production sites. Kowa Company, Ltd., operating from Nagoya, develops and supplies DMC across industrial solvent, battery, and pharmaceutical channels, with production and distribution networks spanning Japan and the United States. Kishida Chemical Co., Ltd., based in Osaka, emphasizes high-purity grades produced via transesterification, serving laboratory, industrial, and pharmaceutical applications.
In the high-purity and reagent space, Merck KGaA, headquartered in Darmstadt, supplies DMC as a high-purity solvent and reagent for pharmaceutical and chemical synthesis, with offerings that also extend into battery-electrolyte grade options. On the large-scale production side, Shandong Shida Shenghua Chemical Group Co., Ltd. and Hualu Hengsheng Group Co., Ltd., both operating in Shandong, China, represent substantial manufacturing capacity built on methanol oxidative carbonylation and transesterification pathways, supplying industrial, battery, and pharmaceutical grades with ongoing capacity upgrades. Tokyo Chemical Industry Co., Ltd. (TCI) contributes to the research and industrial grade market with high-purity offerings for synthesis and battery applications, while Dongying City Longxing Chemical Co., Ltd. serves solvent and polycarbonate precursor demand with battery-grade capacity as part of the broader Chinese manufacturing ecosystem.
Recent corporate activity underscores how aggressively firms are positioning themselves for the next phase of demand growth. In February 2026, UBE Corporation initiated groundbreaking and construction for a new DMC and EMC plant in Louisiana, USA, targeting 100,000 tons per year of DMC capacity, with operations planned for the second half of fiscal 2026 to address North American battery and semiconductor demand. Earlier, in November 2025, Jiangsu Sailboat Petrochemical Co., Ltd. collaborated with Asahi Kasei on a new high-purity DMC and ethylene carbonate facility in Lianyungang, China, aimed at increasing battery-grade supply. These developments reflect a broader pattern: capacity additions are increasingly tailored to purity, regional demand proximity, and application-specific requirements rather than undifferentiated volume expansion.
Market Dynamics: Supply, Regulation, and Raw Material Sensitivity
No strategic assessment of the DMC market is complete without examining the external forces that shape cost structures, compliance obligations, and demand elasticity. Raw material dynamics remain a critical lever. Methanol prices in China rose sharply to over USD 400 per ton in March 2026, climbing more than 40% from early March levels amid geopolitical tensions and supply disruptions. Broader Northeast Asian pricing also strengthened, with China FOB prices around USD 425 per metric ton and India FOB prices near USD 807 per metric ton, reflecting tighter supply linked to Middle East disruptions. For producers and downstream buyers alike, methanol cost volatility translates directly into margin pressure, pricing strategy complexity, and inventory timing decisions.
Regulatory and trade developments add further layers of strategic consideration. In July 2025, U.S. Customs and Border Protection issued a ruling classifying Dimethyl Carbonate (CAS No. 616-38-6) from Saudi Arabia, an action with implications for import routing, duty considerations, and sourcing strategy. At the same time, the U.S. EPA continues to reinforce demand for DMC as a low-toxicity green alternative to hazardous solvents under Clean Air Act classifications. This regulatory tailwind supports substitution trends in application segments where environmental compliance, workplace safety, and formulation sustainability are becoming competitive differentiators rather than mere compliance checkboxes.
Lithium Batter Ethylene Carbonate Market
Together, raw material volatility, trade classification developments, and environmental regulation create a market environment in which operational agility matters as much as scale. Producers and buyers must navigate cost pass-through dynamics, ensure continuity of high-purity supply, and align procurement strategies with evolving regulatory expectations. The firms that succeed will be those that treat these dynamics not as isolated risks but as integrated variables in capacity planning, contract structuring, and geographic sourcing.
What the Report Delivers: Actionable Intelligence for Executive Decision-Making
This market research study is designed to move beyond high-level characterization and into the practical judgments that executives, commercial leaders, and strategy teams need to make in 2026 and beyond. The report provides a structured, evidence-based view of the DMC market that supports capital allocation, procurement planning, product portfolio strategy, and competitive benchmarking. It integrates historical performance, forecast trajectories, segment-level analysis, and company-level intelligence into a single decision-support framework.
Readers will find detailed coverage of market sizing and growth modeling across the forecast period, with a clear delineation of how revenue is distributed by grade, application, and region. The analysis includes competitive profiling of the principal participants, examining production routes, grade focus, geographic presence, and recent capacity or partnership developments. It also contextualizes market behavior within the broader environment of raw material pricing, regulatory change, and trade classification actions that influence both supply economics and demand patterns. Importantly, the report connects these observations to strategic implications: where demand is structurally strengthening, which grade and application combinations offer the most compelling value creation potential, and how competitive concentration shapes bargaining power, differentiation opportunities, and market entry considerations.
By presenting a comprehensive but curated view of the market, the study enables organizations to identify where to deepen investment, where to manage exposure, and where to monitor emerging shifts that could alter the competitive landscape. It is built for teams that require more than aggregate market numbers; they need the analytical scaffolding that turns data into informed action.
Strategic Implications for 2026 and Beyond
The DMC market’s projected trajectory offers a compelling case for proactive strategic engagement. With the market expected to advance from a 2026 valuation of USD 1,791.63 million to USD 2,896.00 million by 2032 at a CAGR of 8.1%, the growth runway is substantial, but it is not uniformly distributed. Value creation will increasingly favor participants who can align capacity with grade-specific demand, secure reliable methanol input economics, and position for application-driven growth in polycarbonate synthesis, battery electrolytes, and specialty solvents. Geographic and regulatory diversity will further reward firms that can manage supply chain resilience while capitalizing on sustainability-driven substitution trends.
In this context, the strategic questions facing industry leaders are clear. How should capacity investments be prioritized across industrial, pharmaceutical, and battery grades? Which application segments offer the strongest combination of volume growth and margin resilience? How should procurement and sourcing strategies adapt to methanol price volatility and evolving trade classifications? And where do competitive dynamics create room for differentiation through purity, service, or regional proximity? Answering these questions requires detailed intelligence that connects market structure to operational and commercial decision-making.
Next Steps: Accessing the Full Intelligence Suite
This overview provides a high-level framing of the market environment and the strategic value embedded in our latest DMC market research. It is intended to demonstrate the depth and relevance of the analysis while preserving the detailed segmentations, regional breakdowns, application-level revenue distributions, and company-specific assessments that constitute the full report. For organizations seeking to make precise, evidence-based decisions in 2026, the complete study offers the granularity required to translate macro trends into executable strategy.
To access the full market sizing across segments, detailed forecast tables, competitive profiles, and the complete analysis of market dynamics and strategic implications, visit the full report page. The complete intelligence suite is structured to support executive review, commercial planning, and investment evaluation with the specificity that contemporary DMC market decisions demand.
For detailed analysis of this topic, please visit the official page: Dimethyl Carbonate (DMC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microducts Market Hits $4.84B in 2025, Projected 11.3% CAGR Through 2032
By pmarketresearch, 2026-09-15
Microducts Market Strategic Outlook 2026: Navigating the Next Wave of Fiber Infrastructure Investment
The global telecommunications landscape is undergoing a structural transformation driven by accelerating bandwidth demand, the maturation of fiber-to-the-x (FTTX) architectures, and the relentless push toward low-latency, high-density connectivity. At the heart of this transition lies a critical yet often underestimated physical layer component: microducts. As network operators, infrastructure investors, and municipal planners confront the operational realities of hyperscale fiber deployment, the microducts market has evolved from a commoditized conduit segment into a strategically differentiated infrastructure category. Our latest market research delivers a comprehensive, data-grounded assessment of this sector, offering enterprise decision-makers a clear line of sight into the forces that will shape capital allocation, supply chain strategy, and competitive positioning through 2032.
This briefing serves as a strategic preview of that research. It outlines the macro trajectory of the market, dissects the operational and regulatory dynamics currently reshaping competitive behavior, and demonstrates why forward-looking organizations are treating microduct infrastructure intelligence as a core component of their 2026 planning cycles. What follows is designed to establish analytical credibility while pointing toward the full report as the definitive source for actionable intelligence.
Microducts Market
Market Trajectory and the Strategic Imperative for 2026
The microducts market has demonstrated consistent, compounding growth over the past half-decade, transitioning from an estimated 2.82 billion USD in 2020 to approximately 4.84 billion USD by 2025. This trajectory reflects more than incremental demand; it signals a structural expansion in how fiber networks are architected, deployed, and scaled. Looking ahead, the market is projected to surpass the 5.5 billion USD threshold in 2026, with growth momentum carrying the sector toward the 10 billion USD mark by 2032. The intervening years will be characterized by an 11.3 percent compound annual growth rate, a figure that underscores the velocity at which fiber infrastructure investment is translating into tangible demand for precision-engineered microduct systems.
For enterprise strategists, these numbers carry a deeper implication. The growth curve is not linear across all deployment contexts, nor is it evenly distributed across product architectures or geographic markets. Rather, it reveals a market in which certain network topologies, installation methodologies, and material specifications are capturing disproportionate share. Understanding where growth concentrates, why it concentrates there, and how leading operators are positioning themselves to capture it requires more than top-line forecasting. It demands a granular, scenario-aware analysis that maps demand drivers to supply-side capabilities, regulatory constraints, and technological maturity curves.
Our research framework integrates historical performance data with forward-looking modeling to isolate the inflection points that will matter most to 2026 decision-makers. By examining the interplay between network architecture evolution, material cost dynamics, and deployment standardization, the study provides a structured basis for evaluating market entry timing, capacity investment, procurement strategy, and partnership alignment. The objective is not simply to report where the market is heading, but to equip leaders with the analytical scaffolding necessary to act before competitive advantages solidify.
Competitive Positioning and the Reshaping of the Vendor Landscape
The microducts market is defined by a moderately concentrated competitive environment, with a small cohort of established manufacturers commanding a meaningful share of global supply. This concentration does not imply market rigidity. On the contrary, recent developments reveal a landscape marked by targeted capacity expansion, certification-driven differentiation, and strategic collaboration aimed at hardening end-to-end fiber delivery pathways.
Leading players are pursuing competing strategies that reflect divergent interpretations of where value will accrue. Some manufacturers are doubling down on specialized microduct architectures, emphasizing blown fiber compatibility, multi-duct bundling efficiency, and flame-retardant performance for indoor and multi-dwelling unit applications. Others are scaling production capabilities to support broadband expansion initiatives, while a subset of industry participants are forging partnerships that bridge microduct supply with hardened connectivity solutions and network extension frameworks. The result is a market in which product specification, installation methodology, and certification compliance are becoming as strategically consequential as unit cost.
Recent operational milestones illustrate this dynamic with precision. Capacity expansions have been announced to accommodate additional production lines for microduct and microduct bundle manufacturing, signaling confidence in sustained European and regional broadband demand. Certification achievements have reinforced the credibility of micro-trenching and direct installation methodologies, validating microduct systems as viable components of high-visibility infrastructure projects. Facility upgrades have highlighted the deployment of next-generation multi-production configurations aligned with broadband rollout targets, while strategic partnerships have begun to integrate blowable fiber optic micro-cable solutions into hardened connectivity ecosystems. Simultaneously, upstream procurement frameworks between major network operators and fiber suppliers have extended multi-year agreements that indirectly reinforce demand visibility for microduct infrastructure.
These developments matter because they reveal a market in which competitive advantage is increasingly derived from operational readiness, specification alignment, and ecosystem integration rather than scale alone. Our analysis maps these strategic moves against market concentration metrics, regional deployment patterns, and application-specific demand profiles to identify where vendor positioning is likely to translate into durable share gains. The full report examines these dynamics in depth, providing a structured competitive assessment that enables buyers, investors, and operators to evaluate supplier reliability, innovation trajectories, and long-term strategic fit.
Regulatory, Material, and Operational Dynamics Influencing Procurement and Deployment
No strategic assessment of the microducts market is complete without acknowledging the regulatory and input-cost environment that governs what can be deployed, where it can be installed, and at what marginal cost. The intersection of standards compliance, material availability, and logistical friction is actively reshaping procurement behavior across the value chain.
On the standards front, industry certification frameworks continue to serve as gatekeepers for installation approvals, particularly in contexts requiring fire-rated performance or outdoor durability. Building codes across the European Union and North America are increasingly mandating flame-retardant microduct variants for indoor and multi-dwelling installations, elevating material specification from a technical preference to a compliance requirement. Concurrently, technical standards governing microduct diameters and microcable blowability are defining the practical parameters for fiber-to-the-home deployments, constraining design flexibility while simultaneously reducing deployment variability. These regulatory and technical anchors create a predictable baseline for procurement but also raise the stakes for manufacturers that must align product portfolios with evolving approval pathways.
Material dynamics introduce a parallel layer of strategic complexity. HDPE remains the primary feedstock for microduct production, and volatility in HDPE pricing has placed margin pressure on manufacturers operating amid ongoing geopolitical oil supply dynamics. Upstream resin logistics and geopolitical factors have translated into effective cost increases for HDPE microduct grades, compressing the margin between raw material expenditure and finished product pricing. In this environment, procurement strategies that rely solely on historical cost assumptions risk underpricing projects or overcommitting to fixed-price contracts without adequate exposure management.
These forces do not operate in isolation. Regulatory specification requirements interact with material cost trajectories to influence which product types become preferred in specific deployment scenarios. Installation methodologies that minimize civil works exposure may gain favor in cost-sensitive environments, while standardized microduct diameters and certified flame-retardant variants may become default choices where compliance risk outweighs marginal savings. Our research integrates these dynamics into a unified operating context, enabling stakeholders to evaluate how regulatory compliance, feedstock volatility, and logistical surcharges will shape total cost of ownership, supplier selection, and deployment scheduling through the forecast period.
Pre-Wired Conduits Market
What the Full Research Delivers for Enterprise Decision-Makers
The macro trajectory, competitive movements, and regulatory and material dynamics outlined above constitute only the surface layer of the market environment. Translating this context into executable strategy requires a deeper, more structured intelligence layer—one that connects demand segmentation, application-specific adoption patterns, product-type preferences, and regional deployment intensity to the operational decisions facing leadership teams in 2026.
The complete research study is designed to serve that function. It moves beyond aggregate forecasting to provide a multidimensional assessment of the microducts market, linking historical performance data with forward-looking modeling across the forecast horizon. The analysis examines how demand propagates across network architecture types, how product architectures align with installation methodologies, and how application contexts differentiate growth velocity and margin profiles. It also situates vendor behavior within a competitive framework that accounts for market concentration, strategic partnerships, certification milestones, and capacity investments, offering a structured basis for evaluating supplier resilience and long-term positioning.
Equally important, the study embeds market dynamics into practical decision-support frameworks. Procurement teams can use the analysis to benchmark supplier landscapes, anticipate specification shifts, and model cost exposure under varying material and logistics scenarios. Network planners and infrastructure investors can leverage the segmentation analysis to identify where deployment intensity, regulatory pressure, and product-fit alignment are most likely to generate durable demand. Strategic leaders can draw on the competitive and dynamic assessments to time market entries, structure partnerships, and calibrate capacity commitments in a way that balances growth opportunity against cost uncertainty.
Accessing the full report provides the granularity necessary to convert high-level market awareness into targeted action. The detailed segmentation analysis, the application- and product-type breakdowns, and the regional demand distributions are presented with the precision required for operational planning and investment evaluation. These elements are intentionally developed to support scenario testing, supplier comparison, and procurement calibration, ensuring that decision-makers can move from strategic intent to execution with confidence.
Conclusion: Why 2026 Demands Precision Intelligence
The microducts market is entering a phase in which growth is no longer the only metric that matters. The strategic question for 2026 is how to capture that growth efficiently, compliantly, and with a supply chain and partner ecosystem capable of sustaining deployment velocity amid material volatility and specification evolution. The companies that will navigate this environment most effectively are those that treat microduct infrastructure not as a passive procurement category but as a strategically managed layer of the broader fiber architecture.
Our research was constructed to support precisely that shift in mindset. By integrating historical trajectory, competitive behavior, regulatory and material dynamics, and forward-looking growth modeling, the study provides a coherent intelligence foundation for enterprise decision-makers seeking to align investment, procurement, and deployment strategies with market reality. The aggregate figures referenced here establish the scale and direction of the opportunity. The full report delivers the segmentation depth, competitive detail, and operational context needed to act on it.
For leaders preparing 2026 capital plans, supplier evaluations, and deployment roadmaps, the distinction between high-level awareness and actionable intelligence will define execution quality. The complete market research closes that gap, transforming macro momentum into structured, decision-ready insight.
For detailed analysis of this topic, please visit the official page: Microducts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Slewing Bearings Market to Reach $652.66 Million by 2032 with 5.95% CAGR
By pmarketresearch, 2026-09-15
Navigating the Turn: Strategic Insights into the 2026 Slewing Bearings Market
Executive Overview
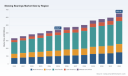
The global slewing bearings market stands at a critical inflection point. Between 2020 and 2025, the industry demonstrated remarkable resilience, expanding from a revenue base of 331.45 million USD to 438.27 million USD. This historical trajectory underscores a consistent demand cycle driven by heavy infrastructure investment and the modernization of industrial machinery. As we project forward into the forecast period of 2026 through 2032, the market is poised to reach a valuation of 652.66 million USD by the end of the decade.
For enterprise leaders and procurement strategists, understanding this growth curve is not merely about tracking revenue; it is about anticipating supply chain constraints, technological shifts, and competitive realignments. The Compound Annual Growth Rate (CAGR) indicating a steady expansion at approximately 5.95 percent suggests a mature yet evolving landscape. This article serves as a strategic primer, drawing from the comprehensive PW Consulting Slewing Bearings Market Research, to highlight the operational realities defining the 2026 business environment.
Macroeconomic Trajectory and Growth Drivers
The market expansion from 2020 to 2025 was characterized by steady volume increases across key industrial sectors. The revenue progression from 358.19 million USD in 2021 to 395.93 million USD in 2023 highlights the post-pandemic recovery velocity. By 2026, the market is expected to breach the 472.72 million USD threshold. This growth is not linear but is propelled by specific macroeconomic engines that require nuanced understanding.
Primary growth vectors include the ongoing transition in energy infrastructure and the persistent need for heavy lifting solutions in construction and mining. However, the forecast period from 2027 to 2032 reveals an acceleration in value accumulation. The jump from 478.24 million USD in 2027 to 560.44 million USD in 2029 indicates that market maturity is bringing higher value density per unit, rather than just volume growth. Strategic planners must note that while the top-line revenue is expanding, the underlying cost structures are facing significant pressure from raw material volatility.
The reliance on steel-intensive manufacturing means that fluctuations in alloy steel such as 42CrMo directly impact manufacturing costs and fatigue life of the raceway. Industry market data from mid-2026 suggests that these material constraints are compressing profit margins for slewing bearing manufacturers. Consequently, the revenue figures reported in market sizing must be interpreted alongside margin analysis to understand true profitability potential in the coming years.
Segmentation Dynamics: Type and Application
The market structure is defined by distinct technological and application-based segments. In terms of product typology, the landscape is bifurcated between Roller Slewing Bearings and Ball Slewing Bearings, with a smaller portion occupied by other specialized types. The Roller segment continues to hold significant share due to its load-bearing capabilities in heavy machinery, while the Ball segment remains critical for precision applications requiring lower friction and higher rotational speeds.
Application-wise, the demand is diversified but concentrated in high-capital sectors. Renewable Energy remains a pivotal driver, reflecting the global push toward wind turbine installation and maintenance where slewing bearings are integral to yaw and pitch systems. Construction and Transit Equipment follows closely, driven by excavators, cranes, and tunneling machinery. Industrial Machinery and Mining sectors contribute substantial volumes, while miscellaneous applications round out the portfolio.
It is crucial for strategy teams to recognize that these segments do not grow in isolation. The interplay between renewable energy installation cycles and construction equipment demand creates complex demand forecasting challenges. A detailed breakdown of how these segments interact, including specific volume contributions and regional variances, is essential for accurate budgeting and capacity planning. Readers seeking precise segmentation splits and application-specific revenue breakdowns are advised to consult the full market intelligence report to avoid strategic misalignment.
Competitive Landscape and Key Players
The market concentration metrics indicate a moderately fragmented environment. The CR3 stands at 24.6 percent, and the CR5 extends to 32.1 percent. This suggests that while key multinational corporations hold significant influence, there is ample room for specialized players and regional manufacturers to compete on customization and price.
Prominent entities shaping the competitive terrain include SKF, headquartered in Göteborg, Sweden. As a manufacturer of standard and customized slewing bearings with outside diameters ranging from 0.1 to 18 m, SKF sets a benchmark for precision and scale. Similarly, Kaydon Bearings, based in Muskegon, Michigan, USA, supplies slewing ring bearings and thin section bearings, including specific solutions for wind energy applications.
Thyssenkrupp Rothe Erde, operating out of Germany, remains a global leader in large-diameter slewing bearings up to 25,000 mm, with facilities spanning Asia, Europe, and the Americas. Their recent operational updates, including plans to consolidate operations to Aurora in 2026, signal strategic shifts in manufacturing footprints that could affect supply chain reliability in North America.
Other notable participants include Scheerer Bearing Corporation in Willow Grove, Pennsylvania, known for high-quality slewing ring bearings and drives. SlewPro, based in Hudson, Massachusetts, focuses on precision custom slewing rings, drives, and gears for U.S. OEMs, highlighting the niche for localized customization. TGB Group in Italy leads in high-quality slewing rings for demanding environments, while Silverthin Bearing Group in Preston, Washington, produces precision thin section and slewing ring bearings for aerospace, robotics, and industrial uses.
In the Asia-Pacific region, LDB Bearing in Luoyang, Henan, China, manufactures slewing bearings, slew drives, and gears for heavy machinery and cranes. Fenghe Slewing Bearing operates as a custom OEM/ODM manufacturer, often replacing SKF and Kaydon equivalents, while QCB in the United Kingdom supplies slewing rings, drives, and thin section bearings with diameters from 100 mm to over 10,000 mm.
The competitive dynamics are further fluidified by recent corporate activities. In July 2025, Silverthin Bearing Group released a new comprehensive catalog for thin section and slewing ring bearings targeting space, aerospace, defense, robotics, medical, oil and gas, and semiconductor industries. This expansion into high-tech sectors diversifies their revenue base beyond traditional industrial uses. Meanwhile, Xuzhou Wanda Slewing Bearing Co., Ltd. exhibited slewing bearings and drives at CONEXPO-CON-AGG 2026 in Las Vegas, signaling aggressive market penetration in the construction sector. LDB Bearing also joined as an exhibitor at bauma CONEXPO INDIA 2026, reinforcing the commitment of Chinese manufacturers to global trade shows and direct customer engagement.
Understanding the specific strengths, weaknesses, and strategic moves of each competitor is vital for positioning. The full market report provides a detailed competitive benchmarking analysis that goes beyond company profiles to assess market share dynamics and strategic maneuvering.
Regulatory and Operational Dynamics
The operational environment for slewing bearings is increasingly shaped by regulatory frameworks and technical standards. A significant development occurred in June 2026 with the introduction of ISO 16123:2025. This standard specifies design, manufacture, and acceptance requirements for slewing bearings in marine cranes at ambient temperatures not lower than −40 °C. Compliance with this standard is becoming a prerequisite for bidding on offshore and marine construction contracts, effectively raising the barrier to entry for manufacturers not equipped for extreme condition engineering.
Simultaneously, the European Union introduced new guidelines to ensure the sustainability of bearing manufacturing processes. These guidelines emphasize reduced carbon footprints and enhanced recycling practices. For global suppliers, this means that sourcing strategies and production methodologies in Europe must align with stricter environmental compliance, potentially increasing operational costs but also creating differentiation opportunities for early adopters of green manufacturing.
Raw material dynamics remain a persistent headwind. The fluctuation in costs of specialty steel and rare earth elements poses a substantial restraint on production. As previously noted, slewing bearings are steel-intensive, with fluctuations in alloy steel such as 42CrMo directly impacting manufacturing costs and fatigue life of the raceway. Supply chain managers must develop hedging strategies or long-term supplier contracts to mitigate these risks. The market report offers a deep dive into cost structure analysis and raw material trend forecasting to assist in these mitigation efforts.
External Tooth Slewing Bearing Market
Strategic Implications for 2026 Decision Makers
As we navigate 2026, the slewing bearings market offers both opportunities and challenges that require decisive action. The growth trajectory toward 652.66 million USD by 2032 is clear, but the path to capturing value within that growth is complex. Decision makers must evaluate their supply chain resilience against raw material volatility. They must assess their compliance readiness regarding ISO 16123:2025 and EU sustainability guidelines. Furthermore, they must analyze their competitive positioning relative to giants like Thyssenkrupp Rothe Erde and specialized players like Silverthin or SlewPro.
The consolidation of operations by key players, such as the relocation plans announced by thyssenkrupp rothe erde USA in May 2026, indicates a shift in logistics and distribution networks. Procurement teams need to anticipate how these geographic shifts will impact lead times and delivery reliability for North American operations.
For investors and strategic planners, the moderate market concentration (CR5 at 32.1 percent) suggests that M&A activity or strategic partnerships could reshape the landscape. Acquiring niche capabilities in thin section bearings or expanding into high-growth applications like renewable energy could yield significant returns. However, without granular data on segment profitability and regional growth rates, such moves carry risk.
This article has highlighted the macro trends, competitive players, and regulatory shifts defining the current market. However, the depth of insight required to formulate a winning strategy demands more than surface-level trends. The PW Consulting Slewing Bearings Market Research provides the actionable data needed to navigate these complexities, including detailed segmentation analysis, regional revenue splits, and comprehensive company profiling.
To secure your organization's position in this evolving market, access to precise intelligence is paramount. We invite you to explore the full report for complete segmentation data, detailed competitive analysis, and strategic forecasts that will inform your 2026 and beyond planning.
Slewing Bearings Market
For detailed analysis of this topic, please visit the official page: Slewing Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biologics & Biosimilars Market Hits $527.36B in 2025, Projected 10.42% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Biologics and Biosimilars Market: Strategic Intelligence for 2026 and Beyond
The global biologics and biosimilars landscape is undergoing a structural transformation that demands immediate and informed strategic attention. As biosimilar adoption accelerates across developed and emerging healthcare systems, organizations that fail to anticipate regulatory shifts, manufacturing bottlenecks, and reimbursement realignments risk ceding competitive ground to agile entrants. Our newly released research framework maps this trajectory with precision, delivering an operational blueprint for executives navigating pricing pressure, portfolio optimization, and geographic expansion.
The market has demonstrated consistent momentum over the past half-decade, having moved from a baseline of 321.27 billion USD in 2020 to an estimated valuation of 527.36 billion USD in 2025. Forecasts indicate sustained expansion through 2032, with the trajectory expected to reach 1.055 trillion USD by the final year of the projection window. Crucially, the compound annual growth rate for this interval stands at 10.42 percent, reflecting not merely incremental uptake but a fundamental restructuring of how therapeutic proteins and their follow-on counterparts are adopted, reimbursed, and manufactured at scale. For corporate leadership teams evaluating 2026 budgeting, capacity investments, and partnership strategies, these figures are not abstract benchmarks. They signal an environment where speed-to-market, regulatory navigation, and supply chain resilience will separate market leaders from reactive followers.
Why 2026 Requires a Strategic Overhaul
Corporate planning cycles traditionally treat biologics and biosimilars through a narrow commercial lens, yet the coming year will expose structural fault lines across the value chain. Reimbursement models continue to lag inflationary pressures, with hospital networks facing mounting underpayments that constrain procurement flexibility and shift negotiation leverage toward manufacturers who can demonstrate consistent quality and reliable supply. Simultaneously, regulatory pathways are being recalibrated to reduce development friction while preserving safety standards. The cumulative effect is a market where pricing architecture, interchangeability designations, and manufacturing scalability become equally decisive. Organizations that continue relying on legacy portfolio assumptions will find themselves misaligned with procurement priorities, payer expectations, and competitive entry timing.
Rather than treating this environment as a series of isolated challenges, executive teams need an integrated view of how approval cadence, international sourcing dependencies, input cost volatility, and regional demand patterns intersect. Recent market intelligence confirms that biosimilar adoption remains constrained relative to therapeutic spending, with approved follow-on products representing a substantial share of total pharmaceutical expenditure while capturing a smaller portion of actual utilization. This gap is not an anomaly; it reflects payer hesitation, formulary optimization cycles, and the operational complexity of switching protocols. Understanding where that gap closes first, and which therapeutic categories unlock faster uptake, will shape marketing authorization strategies, manufacturing commitments, and commercial launch sequencing throughout 2026.
What the Research Delivers
Our Biologics and Biosimilars Market study was designed to convert macro trends into executable decision support. Rather than offering high-level commentary, the analysis is structured around the operational variables that procurement, regulatory, and commercial teams encounter daily. The report integrates historical performance data from 2020 through the current base year with a forward-looking forecast spanning 2026 to 2032, enabling scenario modeling that accounts for approval timing, regional reimbursement evolution, and manufacturing cost dynamics.
Readers will find a coordinated set of analytical modules that address:
- Comprehensive market sizing and trajectory mapping, anchored to verified historical baselines and calibrated forecast intervals that support capital allocation and capacity planning
- Structural segmentation analysis across therapeutic classes and application categories, allowing portfolio teams to identify concentration risks, growth pockets, and substitution exposure
- Regional demand mapping that contextualizes procurement patterns, payer behavior, and market entry timing without relying on superficial geographic snapshots
- Competitive benchmarking against established multinational manufacturers and specialized biosimilar developers, including product portfolio reach, approval momentum, and commercialization infrastructure
- Supply chain and manufacturing risk assessment, covering single-use system dependencies, active pharmaceutical ingredient sourcing exposure, and cost sensitivity under shifting trade conditions
- Regulatory and reimbursement dynamics, including recent designation changes, guidance simplifications, and the operational impact of approval cadence on interchangeable product development
- Strategic scenario frameworks that translate data into prioritization logic for launch sequencing, partnership evaluation, and market access planning
Each section is built to answer a practical question: where should resources be deployed, which therapeutic categories warrant accelerated development or licensing focus, and how should organizations position manufacturing and distribution assets to buffer against input cost volatility? The intent is to provide decision-makers with a structured reference point that can be integrated directly into annual planning, risk assessments, and partnership diligence.
Competitive Landscape: Who Is Moving and Why
The current competitive environment is defined by a blend of scaled multinational portfolios and focused biosimilar specialists. Several organizations have built substantial follow-on biologics pipelines, while others are leveraging recent approvals to accelerate commercialization in therapeutic areas where originator exposure remains high. Amgen continues to expand its biosimilar footprint with commercialized products spanning oncology and bone metabolism indications, reflecting a deliberate strategy to convert portfolio depth into recurring commercial value. Pfizer has reinforced its presence through operational growth in select biosimilar categories, supported by manufacturing infrastructure designed to sustain launch velocity and supply reliability.
Sandoz has maintained its positioning as a dedicated follow-on biologics leader, advancing multiple approvals and launch activities that reinforce its focus on high-quality biosimilar development. Celltrion is executing a broader expansion plan that extends its biosimilar product roadmap through the late 2030s, complemented by recent U.S. facility activation and product introductions that broaden market access. Biocon Biologics has strengthened its commercialization base with multiple approved biosimilars and recent regulatory clearances, while Alvotech is pushing forward with biosimilar programs targeting high-spend immunology assets and has advanced recent approvals and launch activity.
Specialized developers are also shaping competitive dynamics. Formycon has concentrated on ophthalmology biosimilars with multiple FDA-approved candidates and recent launch milestones. Samsung Bioepis continues to build a diversified approval portfolio, leveraging U.S. commercialization partnerships to extend reach for recent denosumab and other biosimilar introductions. Fresenius Kabi has integrated biosimilar offerings into broader therapeutic portfolios, with ongoing regulatory activity supporting oncology and inflammatory treatment options. Together, these organizations illustrate a market where differentiation emerges not only from approval count but from manufacturing readiness, interchangeability strategy, and the ability to convert approvals into durable commercial execution.
Regulatory and Reimbursement Pressures Reshaping Market Behavior
Regulatory evolution remains one of the most influential forces guiding biosimilar development and adoption. Recent guidance efforts have aimed to simplify biosimilarity study requirements and reduce development friction for interchangeable designations, signaling a regulatory posture that favors faster pathway execution without compromising evaluation rigor. Approval activity has reflected this direction, with multiple biosimilar products receiving clearance across therapeutic indications during recent months, including developments in immunology, ophthalmology, and bone metabolism categories.
These approval patterns matter because they influence formulary inclusion speed, switching confidence, and procurement planning. Yet regulatory clearance alone does not guarantee market penetration. Payer and hospital economics remain under strain, with reimbursement structures for biologics trailing inflationary cost movements. This mismatch complicates commercialization for manufacturers and creates procurement uncertainty for providers, especially when biosimilar substitution requires coordinated clinical workflows and contracting adjustments. Organizations that account for these reimbursement constraints in their launch planning will be better positioned to align pricing, contracting, and market access support with the realities of institutional buying behavior.
Supply Chain Realities and Cost Dynamics
Behind the approval headlines lies a supply environment that directly shapes margin durability and supply reliability. Biologics manufacturing remains highly dependent on international sourcing, with active pharmaceutical ingredients increasingly concentrated across a limited number of geographies. Sterile injectable production is similarly exposed to concentrated manufacturing bases, creating structural sensitivity to logistics disruption, quality audits, and sourcing continuity. These dependencies are not abstract procurement concerns. They influence production scheduling, inventory strategy, and the ability to meet launch demand without compromising consistency.
Worldwide Aflibercept Biosimilars Market
Compounding these structural dependencies are cost pressures tied to input inflation and trade policy. Recent analysis indicates that tariff exposure on single-use systems and related manufacturing inputs has raised production costs for monoclonal antibody batch operations, with meaningful impact at commercial scale. For organizations planning capacity expansion or new product introductions, this implies that cost modeling must incorporate not only direct manufacturing expenses but also scenario sensitivity around input availability, logistics friction, and regional sourcing diversification. Companies that treat supply chain resilience as a secondary operational concern will face greater exposure when launching products that rely on consistent batch output and predictable cost structures.
How to Use This Research for 2026 Decision-Making
The strategic value of this research lies in its ability to convert broad market signals into prioritized action. Leaders can use the analysis to:
Biologics and Biosimilars Market
- Evaluate portfolio exposure across therapeutic categories and identify where interchangeability, approval momentum, and payer readiness intersect most favorably
- Stress-test manufacturing and sourcing strategies against input cost sensitivity and international dependency risks
- Map competitive entry timing and approval cadence to anticipate substitution pressure and adjust pricing or contracting assumptions accordingly
- Align commercial launch planning with regional procurement patterns and reimbursement conditions rather than relying on generic adoption curves
- Support partnership and licensing decisions with competitive benchmarking that reflects both portfolio breadth and execution capability
For organizations managing multiple development programs or planning biosimilar market entry, the study provides a structured reference for balancing speed, quality, and commercial feasibility. For established manufacturers, it offers a framework for assessing where portfolio reinforcement, regional expansion, or supply chain diversification will yield the strongest return under current market conditions.
Conclusion
The biologics and biosimilars market is entering a phase where growth is no longer the only metric that matters. Execution quality, regulatory alignment, reimbursement navigation, and supply chain discipline will determine which organizations convert market expansion into durable competitive advantage. The trajectory projected through 2032 reflects substantial opportunity, but realizing that opportunity requires decision-making grounded in detailed market intelligence rather than generalized industry narratives.
Our full Biologics and Biosimilars Market research report extends far beyond the strategic overview presented here. It delivers the complete dataset, segmentation analysis, competitive benchmarking, regulatory tracking, and scenario frameworks required to support confident planning across 2026 and the forecast period ahead. For executive teams, procurement leaders, and commercial strategists seeking to move from observation to action, the complete study provides the depth necessary to translate market momentum into measured, defensible decisions.
For detailed analysis of this topic, please visit the official page: Biologics and Biosimilars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sterile Medical Packaging Market Hits $501M in 2025, Projects 7.65% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Sterile Medical Packaging Market: Navigating Growth Amid Regulatory Precision and Material Innovation
The global healthcare ecosystem depends on an often-overlooked foundation: sterile medical packaging. As therapeutic modalities grow increasingly complex and supply chains stretch across continents, the integrity of packaging has become inseparable from patient safety, regulatory compliance, and commercial viability. Our newly released market research offers a comprehensive, forward-looking blueprint for executives, procurement leaders, and strategic planners who must navigate the sterile medical packaging landscape through the end of the decade. This briefing outlines the macro trajectory, competitive architecture, regulatory currents, and operational imperatives that will define portfolio strategy, capital allocation, and risk management from 2026 onward.
Plastic Medical Packaging Market
Over the past half-decade, the sector has demonstrated steady, resilient expansion, with the overall market advancing from approximately 350.0 million USD in 2020 to an estimated 501.01 million USD in 2025. Looking ahead, the forecast period through 2032 points to continued momentum, with the market projected to reach 834.21 million USD by the terminal year of the analysis window. The implied compound annual growth rate of 7.65 percent underscores a structurally healthy demand environment, driven by aging demographics, expanding surgical volumes, and accelerating adoption of single-use sterile systems. Yet historical growth alone does not dictate strategic advantage. The real opportunity—and the real risk—lies in how organizations interpret shifting regulatory baselines, material cost dynamics, and the concentration of market power while positioning themselves for sustained, defensible performance.
Sterile Medical Packaging Market
Mapping the 2026–2032 Trajectory: What the Numbers Mean for Executive Decision-Making
A 7.65 percent CAGR is not a uniform tailwind. It is a directional signal that rewards segmentation discipline, regional prioritization, and modality-specific packaging engineering. The transition from 501.01 million USD in the base year to a projected 550.33 million USD in 2026 may appear incremental on a spreadsheet, but it reflects a market in which volume growth, premiumization of barrier solutions, and substitution toward higher-performance materials are occurring simultaneously. Organizations that treat the forecast as a single aggregate figure risk misallocating R&D resources, misreading capacity needs, and underpricing contractual commitments. The strategic value of our research lies in its ability to translate this aggregate trajectory into actionable decision layers: where demand is structurally hardening, which application verticals are reshaping supplier requirements, and how geographic exposure should inform localized compliance and distribution footprints. Readers who access the full dataset will find granular breakdowns that enable scenario planning rather than deterministic assumptions.
Competitive Architecture: Concentration, Differentiation, and the Real Source of Advantage
The sterile medical packaging sector remains moderately concentrated, with the top three players collectively commanding roughly a quarter of total revenue and the top five approaching just under 29 percent. This concentration level signals a market where scale, proprietary material science, and entrenched customer relationships matter, yet it also leaves substantial room for specialized suppliers, regional specialists, and agile innovators to capture niche share. The competitive field includes globally recognized suppliers with deep engineering heritage and vertically aligned service models. Amcor, headquartered in Zürich, has built a formidable reputation in thermoformed trays and flexible sterile packaging, consistently emphasizing responsible healthcare solutions that align with sustainability mandates. DuPont de Nemours, based in Wilmington, continues to anchor a significant portion of the flexible barrier market through its Tyvek materials portfolio, supplying sterile pouches, header bags, and lids that are closely associated with medical device protection. West Pharmaceutical Services, operating from Exton, serves the sterile injectable value chain with components and delivery systems designed for rigorous aseptic standards. Sonoco, from Hartsville, provides both rigid and flexible paper-based and composite solutions, while Gerresheimer, headquartered in Düsseldorf, remains a critical voice in glass and plastic primary packaging for sterile pharmaceuticals and medical devices.
The competitive landscape extends well beyond these anchor players. BillerudKorsnäs, based in Stockholm, produces medical-grade paper and paperboard tailored to sterile packaging requirements. Placon, in Oshkosh, specializes in thermoformed medical trays and sterile packaging solutions, and recently expanded its offerings with new lightweight tray designs featuring improved barrier properties. Nelipak Healthcare Packaging, from Fort Worth, provides flexible and rigid sterile packaging for high-volume healthcare applications. Steripack, headquartered in Dublin, focuses on custom sterile medical packaging solutions, and Constantia Flexibles, in Vienna, continues to scale flexible packaging options for sterile medical and pharmaceutical needs. Together, these organizations illustrate a market defined not simply by size but by differentiated capability sets: barrier engineering, thermoforming expertise, glass formulation, paperboard performance, and regulatory documentation fluency. The full competitive analysis in our report examines positioning, strategic overlap, capacity implications, and the evolving tactics that separate market share retainers from share expanders.
Regulatory Density and the Compliance Premium
Few industries operate under a regulatory cadence as intense as sterile medical packaging. In 2026, the compliance environment is tightening across multiple jurisdictions simultaneously, transforming what was once a technical specification exercise into a strategic governance function. The U.S. FDA updated its recognition of ISO 11607-1, referencing the second edition of 2019 with Amendment 1:2023 as the standard for packaging of terminally sterilized medical devices, with full compliance required by December 2026. This timeline is not distant; it dictates near-term testing protocols, validation cascades, and supplier qualification programs for any organization involved in sterile device packaging. Simultaneously, the EU Packaging and Packaging Waste Regulation entered into force in February 2025, establishing a clear architectural shift: all packaging must be recyclable by 2030, with recycled content requirements beginning in 2026 and eco-modulated extended producer responsibility fees applied to producers. For sterile medical packaging suppliers, this means that recyclability is no longer a sustainability aspiration but a design constraint with direct cost implications.
In the United States, the Quality Management System Regulation alignment requirement, which mandates full compliance by February 2026 and aligns with ISO 13485:2016, has further elevated the baseline for quality documentation, traceability, and manufacturing control across sterile packaging operations. Meanwhile, as of March 2026, seven U.S. states—California, Colorado, Maine, Maryland, Minnesota, Oregon, and Washington—have active packaging extended producer responsibility programs that tie producer fees to recyclability and recycled content levels. These state-level frameworks increasingly influence sourcing decisions, especially for suppliers operating across multiple jurisdictions or serving multi-state device manufacturers. The strategic implication is clear: regulatory literacy is now a competitive asset. Organizations that treat compliance as a back-office checklist will face escalating cost leakage and customer qualification friction. Our report maps these overlapping obligations into a practical compliance architecture, helping decision-makers anticipate validation timelines, packaging design constraints, and cross-border regulatory exposure.
Material Economics and the Cost Discipline of Sterile Design
Sterile packaging performance is inseparable from material economics. Barrier integrity, sterilization compatibility, durability during logistics, and compatibility with automated filling lines all depend on raw material behavior, yet pricing volatility can quietly erode margins even when demand remains robust. In April 2026, the Producer Price Index for plastics packaging film and sheet manufacturing stood at 193.699, reflecting sustained pressure on resin and film inputs. This figure is more than a macroeconomic marker; it signals the ongoing operational reality for packaging manufacturers who must balance barrier reliability with cost control. At the same time, material innovation continues to reshape the value proposition. The recent introduction of new lightweight thermoformed tray designs with improved barrier properties illustrates how engineering sophistication can mitigate input cost exposure while enhancing product protection. Similarly, Gerresheimer’s presentation of sustainable flint and amber glass packaging solutions for medical and nutraceutical applications at BIOFACH 2026 highlights the broader industry movement toward material responsibility without sacrificing performance. Our research examines how material choice interacts with sterilization modality, device sensitivity, shelf-life requirements, and recyclability expectations, giving executives a structured lens for evaluating substrate strategies rather than reacting to spot price movements alone.
The Strategic Architecture of the Report
This study is designed for leaders who need to convert market intelligence into executable strategy. It integrates historical performance records with a disciplined forecast framework, enabling readers to test assumptions around volume growth, pricing momentum, and material substitution under multiple scenarios. Beyond the headline trajectory, the report dissects the structural forces shaping supply and demand, including sterilization method compatibility, device complexity trends, healthcare spending patterns, and the operational realities of packaging validation. The segmentation analysis is presented not as a static taxonomy but as a decision matrix, showing how different packaging types, application environments, and geographic exposures interact with cost structures, regulatory expectations, and customer qualification cycles. The competitive profiling extends beyond corporate summaries to examine how major suppliers position themselves across material classes, service capabilities, and regional coverage. Recent developments are incorporated as live indicators of market direction, revealing where investment is flowing, what performance benchmarks are being reset, and which design philosophies are gaining traction. The regulatory overlay is treated as a dynamic factor rather than a static appendix, allowing readers to anticipate where compliance costs will concentrate and where design flexibility may create near-term advantage. For organizations evaluating supplier partnerships, capacity expansion, regional entry, or portfolio rationalization, the full report provides the depth required to support board-level discussion and operational planning.
Forward Positioning: Why the Full Intelligence Matters Now
The sterile medical packaging market is entering a phase in which growth is real, but growth alone does not guarantee profitability or strategic resilience. Margins will be earned through compliance foresight, material engineering rigor, regional regulatory fluency, and a clear understanding of where concentration creates opportunity versus constraint. The difference between reactive sourcing and proactive portfolio strategy will increasingly show up in qualification velocity, cost stability, and customer trust. Our complete market research goes beyond narrative interpretation to deliver the structured quantitative foundation needed to pressure-test assumptions, benchmark competitive exposure, and plan for the 2026–2032 horizon with confidence. For executives who want to move from directional awareness to evidenced strategy, the full report is the next necessary step.
For detailed analysis of this topic, please visit the official page: Sterile Medical Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Infrared Lens Market Hits $192.35M in 2025, Projected to Reach $315.68M by 2032 at 7.52% CAGR
By pmarketresearch, 2026-09-15
Navigating the Infrared Lens Market: Strategic Intelligence for the 2026 Decision Cycle
The infrared (IR) lens market is undergoing a period of structural transformation. Between 2020 and 2025, global revenue expanded from approximately 138.45 million USD to 192.35 million USD, reflecting a steady compound annual growth trajectory that analysts project will sustain a 7.52 percent CAGR through 2032. By the end of the forecast window, the market is expected to surpass 315.68 million USD. These figures, drawn from PW Consulting’s latest infrared lens market research, are more than historical markers. They signal a maturing supply chain, shifting material dependencies, and an intensifying competitive landscape that demands precise, forward-looking strategy.
For executives, procurement leaders, and R&D directors operating in 2026, the question is no longer whether infrared optics will continue to expand, but how to position organizations within a market defined by material scarcity, geopolitical realignment, and rapid product iteration. This article outlines the strategic architecture of our newly released market study, explains why its analytical framework is built for immediate enterprise decision-making, and previews the competitive and operational dynamics that will shape capital allocation, sourcing strategy, and product roadmaps over the next six years.
Why 2026 Demands a More Granular Market Lens
The 2025-to-2026 inflection point is particularly consequential. Forecast data places 2026 revenue at 208.75 million USD, with incremental growth accelerating through 2027 and 2028 before settling into a more measured climb toward 2032. This trajectory masks underlying volatility. Two structural forces are reshaping how infrared optics are sourced, designed, and deployed: raw material supply constraints and regulatory-driven sourcing requirements.
Germanium supply chain disruptions have already translated into extended lead times and pricing adjustments across the IR optics sector. At the same time, export controls on critical materials originating from China have introduced new risk vectors for defense, industrial, and automotive manufacturers. In response, domestic production of alternative materials, including chalcogenide glass, has gained momentum in the United States, creating a parallel supply pathway that reduces reliance on constrained import channels. These dynamics are not peripheral. They directly affect cost structures, time-to-market, and contractual flexibility.
Meanwhile, procurement standards tied to U.S. defense programs increasingly require NDAA-compliant domestic sourcing for infrared lens assemblies. Organizations that have built their supply chains around legacy international suppliers are now confronting compliance gaps that can delay program execution or disqualify bids entirely. The intersection of material scarcity, regulatory compliance, and domestic capacity expansion means that 2026 purchasing and engineering decisions must be informed by more than unit pricing. They require a comprehensive view of supplier resilience, material substitution pathways, and regional production footprints.
Our infrared lens market research is structured to translate these macro-level pressures into actionable intelligence. Rather than presenting static market snapshots, the study maps how supply chain architecture, material innovation, and regulatory frameworks are interacting to redefine competitive advantage.
What the Research Delivers: Operational Intelligence Over Headline Figures
A market study earns its place in the executive workflow when it bridges high-level trends with executable insights. PW Consulting’s infrared lens market report is built around that principle. The analysis begins with historical performance from 2020 through 2025 and extends into a forecast period running from 2026 to 2032, allowing decision-makers to evaluate both retrospective momentum and forward exposure. All figures are denominated in USD and measured in millions, providing a consistent baseline for financial modeling and scenario planning.
Beyond aggregate revenue and CAGR, the report dissects the market across three operational dimensions: type, application, and region. The type breakdown examines the relative positioning of germanium, silicon, and other materials, highlighting how performance requirements and cost constraints are influencing material adoption. The application analysis isolates demand drivers across thermal imaging, night vision, and other use cases, revealing where volume growth is being generated and which segments are experiencing the most intense pricing or specification pressure. The regional assessment maps revenue distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing context for where production capacity, end-user demand, and regulatory environments are converging.
Critically, none of these breakdowns are presented as static percentages or isolated figures. Each segmentation layer is evaluated against supply-side constraints, technological substitution trends, and end-market procurement behavior. This approach ensures that readers understand not just where revenue is concentrated, but why it is concentrated there, what could disrupt that concentration, and how to build strategy around both continuity and change.
Infrared Lens (IR Lens) Market
The report also integrates a competitive landscape assessment that goes beyond company profiles. It evaluates how vertically integrated manufacturers, specialty material producers, and subsystem integrators are positioning themselves across defense, surveillance, automotive, medical, and industrial applications. The analysis considers product portfolio breadth, material strategy, geographic manufacturing presence, and recent commercial activity, allowing readers to benchmark their own capabilities against the firms that are actively shaping market direction.
Competitive Positioning and the 2026 Vendor Landscape
The infrared lens market is characterized by a moderately concentrated competitive structure. CR3 concentration sits at 41.2 percent, while CR5 reaches 58.5 percent, indicating that a relatively small group of established players commands a substantial share of revenue, but that meaningful opportunity remains for specialized and regionally focused manufacturers. The companies that dominate this landscape do so through different strategic levers: vertical integration, material science differentiation, application-specific engineering, and defense-oriented compliance readiness.
LightPath Technologies continues to emphasize vertically integrated production of custom IR lenses and assemblies, with a particular focus on germanium alternatives and mid- to long-wave infrared solutions for defense, surveillance, and thermal imaging. Its strategy reflects a broader industry tilt toward reducing exposure to constrained raw material channels while maintaining performance standards required by high-stakes applications. Umicore has built its presence on high-performance LWIR lenses using proprietary germanium and GASIR chalcogenide glasses, supplying both raw materials and finished assemblies across automotive, medical, and security markets. The company’s integration across material production and assembly illustrates how controlling the upstream supply chain can compress costs and improve delivery reliability.
Tamron has positioned itself around precision optics for uncooled IR lenses, targeting automotive, surveillance, and security applications where volume production and consistency matter as much as optical performance. Ophir Optronics Solutions remains focused on precision IR optics, including continuous zoom lenses spanning MWIR, SWIR, and LWIR bands for defense, security, and industrial use. Its recent product catalog release in 2026 underscores an ongoing push to expand specification flexibility for systems integrators who need adaptive optical configurations. Beijing Lenstech and Kunming Full-wave Infrared Technology represent the growing capability base in China, developing precision IR lenses and uncooled components for thermal imaging and industrial applications, with a notable orientation toward military and civilian thermal systems.
On the defense and high-performance subsystem side, Raytheon and Teledyne FLIR illustrate how EO/IR integration is becoming a strategic differentiator. Raytheon supplies lens assemblies and sub-systems for missile seekers, infrared search and track, and space applications, where performance tolerances and reliability requirements are exceptionally demanding. Teledyne FLIR operates as an OEM provider of custom MWIR/LWIR assemblies and continuous zoom lenses for thermal imaging across defense, automotive, and uncrewed systems, and its 2026 announcement of a new LWIR camera module designed for high-volume production highlights the market’s shift toward scalable, supply-continuous architectures. Edmund Optics and Resolve Optics round out the landscape by serving both stock and custom demand across germanium, zinc selenide, sapphire, silicon, and other substrates, supporting thermal imaging, spectroscopy, CO2 laser, and broader industrial applications.
These profiles are not presented in isolation. The research situates each company within broader supply chain dynamics, material substitution pathways, and application-specific procurement behavior, allowing readers to assess which vendors are best positioned to support particular program requirements, sourcing strategies, or partnership models.
Infrared Detector Market
Recent Developments That Are Reshaping Sourcing and Design Decisions
The market’s direction is being influenced not only by long-term forecasts but by recent product and technology milestones. In early 2026, Flinders University published work on a repairable polymer-based infrared lens using sulfur and organic co-monomers as a sustainable germanium alternative for thermal imaging. While still reflective of academic and applied research momentum, this development signals a continuing interest in material substitution that could, over time, alter cost structures and supply dependencies for specific thermal imaging applications.
At the same time, commercial product activity is accelerating. Ophir Optronics Solutions released its 2026 IR optics catalog, introducing new SWIR and MWIR zoom lenses that expand specification options for systems requiring adaptive field-of-view and resolution profiles. Teledyne FLIR OEM followed with an announcement of a new LWIR camera module optimized for high-volume production and supply continuity, a move that speaks directly to the manufacturing and procurement priorities of organizations seeking predictable availability and scalable integration.
These developments matter because they illustrate the market’s dual trajectory: one thread focused on material innovation and sustainability, another on production scalability and supply assurance. For enterprise planners, the implication is that sourcing strategies cannot be static. Material alternatives, catalog-level specification expansion, and module-level production design are all becoming relevant variables in procurement, product architecture, and risk management decisions.
Strategic Takeaways for the 2026 Decision Cycle
The infrared lens market is expanding, but expansion alone does not guarantee strategic advantage. The firms that will navigate 2026 successfully are those that treat market growth as a backdrop against which sourcing resilience, material strategy, and compliance readiness must be actively managed. Several implications emerge clearly from the current landscape.
- Supply chain diversification is no longer optional. Germanium constraints and export control risks are reshaping lead times, pricing, and program feasibility. Organizations need visibility into alternative material pathways, domestic production capacity, and supplier-level compliance posture.
- Material substitution is moving from research interest to commercial consideration. Chalcogenide glass production and polymer-based lens research are expanding the set of options available for specific thermal imaging and industrial applications. Decision-makers should evaluate where substitution is technically viable, economically justified, and supply-secure.
- Compliance and sourcing origin are becoming competitive requirements. NDAA-aligned domestic sourcing expectations are influencing procurement eligibility for U.S. defense programs. Vendor selection must now account for regulatory alignment as well as optical performance and cost.
- Vertical integration and scalable module design are emerging as differentiators. Companies that control raw material and assembly processes, or that engineer for high-volume production continuity, are better positioned to manage cost and availability pressure across demanding application cycles.
- Competitive concentration creates both risk and opportunity. With CR3 at 41.2 percent and CR5 at 58.5 percent, a small group of players exercises substantial market influence, yet segmentation across materials, applications, and regions leaves room for specialized positioning and targeted partnerships.
These takeaways are not abstract. They directly inform capital planning, supplier qualification, R&D prioritization, and regional sourcing strategy. The full market research study translates each of these themes into structured analysis, enabling organizations to benchmark their exposure, identify vulnerabilities, and prioritize the moves that will matter most over the 2026-to-2032 horizon.
Access the Full Intelligence: Why the Complete Report Matters
The outline above provides the strategic frame, but the detailed segmentation values, competitor positioning matrices, application-level demand drivers, regional revenue distribution, and supply-chain risk mappings are essential for precise decision-making. Those elements are intentionally withheld from this preview so that readers can assess the depth of the full study before committing to the complete dataset and analysis.
The complete infrared lens market research offers a consolidated view of historical performance, forecast trajectory, segmentation dynamics, competitive profiles, recent product and technology developments, and the operational implications of material and regulatory shifts. It is designed for teams that need to align procurement, engineering, and strategy around a single, coherent market picture rather than fragmented data points.
For organizations planning 2026 sourcing strategies, evaluating vendor partnerships, or shaping product roadmaps for thermal imaging, night vision, and adjacent infrared applications, the full report provides the granularity required to move from directional awareness to executable strategy. The market is growing, the competitive structure is evolving, and the firms that act on detailed intelligence will be best positioned to capture value while managing the supply, compliance, and material risks that define this phase of the infrared lens market.
For detailed analysis of this topic, please visit the official page: Infrared Lens (IR Lens) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Paint Protection Film Market Report: $655.5M in 2025, 6.4% CAGR to $1.01B by 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave of Growth: Strategic Insights into the Paint Protection Film Market
The global automotive aftermarket and surface protection industries are undergoing a phase of rapid evolution, driven by heightened consumer awareness of asset preservation, advancements in polymer technology, and a recovering global vehicle production landscape. As businesses look toward 2026 and beyond, the Paint Protection Film (PPF) market stands out as a critical arena for strategic investment and operational adjustment. PW Consulting's latest in-depth market research offers a comprehensive roadmap for stakeholders aiming to capitalize on the projected expansion of this sector.
This analysis serves as an introduction to the broader strategic intelligence contained within our full report. By examining historical trajectories, growth vectors, and competitive dynamics, we highlight the necessity of precise data-driven decision-making in a market characterized by both robust demand and intricate manufacturing complexities.
Market Trajectory and Financial Outlook
Understanding the macroeconomic flow of the Paint Protection Film industry is the first step toward building a resilient business strategy. Our research tracks revenue trends from 2020 through the base year of 2025, providing a solid foundation for forecasting the period from 2026 to 2032. The market has demonstrated consistent resilience, recovering from global supply chain disruptions to establish a steady upward climb in valuation.
TPU Type Paint Protection Film Market
In 2020, the global market began its recovery phase with a valuation reflecting the initial post-pandemic adjustments. Over the subsequent five years, the industry has consolidated its growth, reaching a significant market size by 2025. Looking forward, the momentum is expected to accelerate. The forecast period indicates a compound annual growth rate (CAGR) that suggests sustained expansion rather than speculative spikes. This growth is underpinned by increasing vehicle ownership in emerging markets and the rising adoption of protective films in high-value automotive segments across developed regions.
Strategic planners must note that while the top-line figures indicate healthy growth, the underlying drivers vary significantly by product type and application vertical. The transition from basic protection to premium, self-healing solutions represents a shift in value capture within the supply chain. Our report dissects these value pools without exposing sensitive segmentation data in this summary, ensuring that the full analysis remains a proprietary asset for our clients.
Technology and Material Dynamics
The core of the PPF market lies in material science. The industry has moved beyond simple adhesive films to sophisticated polyurethane-based solutions that offer self-healing properties, hydrophobicity, and exceptional clarity. According to industry market data, polyurethane base films maintain a dominant share in global Paint Protection Film production. This dominance is driven by the material's ability to recover from minor abrasions, thereby extending the aesthetic life of vehicle paint.
Furthermore, TPU films are increasingly recognized as the primary raw material for advanced self-healing and hydrophobic Paint Protection Film. Manufacturers investing in aliphatic TPU technologies are positioning themselves to capture the premium segment of the market, where performance and longevity justify higher price points. The interplay between raw material costs, technological capabilities, and end-user demand creates a complex landscape that requires careful navigation.
Our research details the technical specifications and manufacturing capabilities required to compete at the highest levels. From the USA-based production of aliphatic TPU films to the high-volume manufacturing hubs in Asia, the supply chain is becoming increasingly specialized. Understanding these technological nuances is critical for companies deciding whether to vertically integrate, partner with film manufacturers, or focus solely on distribution and installation.
Key Technical Trends Influencing Strategy
- Self-Healing Capabilities: The demand for films that can recover from stone chips and scratches without visible damage is reshaping product development roadmaps.
- Hydrophobic and Oleophobic Coatings: Enhanced surface energy properties are becoming a key differentiator, reducing maintenance costs for end-users and adding value to installation services.
- Finish Variety: While high gloss remains standard, there is a growing niche for matte and satin finishes, catering to customized automotive aesthetics.
- Installation Efficiency: Pressure-sensitive adhesives and dry-install technologies are being refined to reduce installation time and waste, impacting service center throughput.
Competitive Landscape and Market Concentration
The Paint Protection Film market is characterized by a mix of established multinational corporations and specialized niche manufacturers. Market concentration data indicates a moderately consolidated environment, where a significant portion of revenue is held by key players who have secured strong distribution networks and brand recognition. The CR3 and CR5 metrics highlight the influence of top-tier competitors, yet there remains ample room for innovation-driven entrants.
Geographic diversity in headquarters does not necessarily dictate market reach. Many leading manufacturers based in the United States maintain a global footprint, while powerful manufacturing capacities located in China supply a vast portion of the global demand. This dynamic creates a competitive tension between localized manufacturing benefits, such as faster logistics for North American installers, and cost-effective production scales available in other regions.
Profile of Market Leaders
Our report provides detailed profiles of the entities shaping the industry. These companies are not merely selling film; they are selling comprehensive protection ecosystems.
- LEGEND PPF: With a focus on North American installers, this company manufactures aliphatic TPU-based Paint Protection Film in the USA, emphasizing supply chain localization and support for regional installation networks.
- XPEL Inc.: Known for self-healing Paint Protection Film products, XPEL designs solutions specifically to protect against rock chips, scratches, and scuffs, maintaining a strong brand identity around durability and aesthetic preservation.
- 3M Company: Leveraging its vast industrial portfolio, 3M produces Scotchgard Pro Series Paint Protection Film lines, integrating PPF into a broader suite of automotive protection offerings.
- STEK USA: This manufacturer focuses on hydrophobic and self-healing Paint Protection Film with extreme clarity and depth, offering multiple finishes to cater to diverse consumer preferences.
- UPPF-USA: As a pioneer in advanced Paint Protection Film technology, UPPF-USA maintains control over every product line with in-house manufacturing, a legacy dating back to 1996.
- Pure PPF: Leading the market in bespoke premium colored and clear Paint Protection Film, this company targets the high-end customization segment where personalization is paramount.
- Ceramic Pro: Representing the next evolution in automotive surface protection and durability, Ceramic Pro combines film technology with coating systems to offer comprehensive surface solutions.
- LLumar Films: Their Platinum Paint Protection Film line is often combined with window tinting and ceramic coatings, creating bundled value propositions for installers and consumers.
- TeckWrap International: Specializing in pressure-sensitive adhesive Paint Protection Film, TeckWrap integrates PPF as part of broader automotive film offerings, recently demonstrating dry-install Color Paint Protection Film technology.
- ORAFOL Europe GmbH: Based in Germany, ORAFOL presents an advanced Paint Protection Film range available in high gloss or matte finishes with unmatched clarity, serving the European and global markets.
- Kehui: Located in Shanghai, Kehui positions itself as a global leader in Paint Protection Film manufacturing with a focus on automotive-grade TPU films.
- Sino Vinyl: Based in Guangzhou, this company manufactures High-performance Paint Protection Film to top standards, competing on quality and consistency in the Asian manufacturing sector.
- GSWF: From Zhejiang, GSWF offers Paint Protection Film products as part of high-quality automotive film offerings, targeting both domestic and export markets.
- REEDEE: Based in Guangdong, REEDEE emphasizes Paint Protection Film manufactured to the highest possible standards, focusing on quality control in production.
- Livinyl: Also in Guangdong, Livinyl stands as one of the key manufacturers in China, contributing to the region's significant output in the global PPF supply chain.
Recent Strategic Developments and Industry Context
The competitive landscape is not static. Recent developments indicate that innovation and visibility at major industry events are critical for maintaining market position. Companies are actively showcasing new technologies to gain share and signal technological leadership.
Paint Protection Film Market
For instance, in 2025 and 2026, several key players participated in major exhibitions such as SEMA and Autocosmetica. Ceramic Pro showcased groundbreaking innovations in automotive surface protection including Paint Protection Film at SEMA 2025 with new product lineups and unreleased items. Similarly, LLumar Films participated in the SEMA Show with demonstrations of immersive Paint Protection Film, window film, and ceramic coatings. These events serve as barometers for industry direction, highlighting the convergence of film, coatings, and tinting technologies.
Furthermore, TeckWrap International demonstrated dry-install Color Paint Protection Film technology at Autocosmetica 2026, signaling a shift towards easier installation processes. ORAFOL presented an advanced Paint Protection Film range at the ORAFOL + ISA tradeshow in Orlando. These exhibitions underscore the importance of real-time intelligence gathering. Our report captures these developments to help clients anticipate competitor moves and identify potential partnership opportunities or threats.
Regulatory and Standards Environment
Beyond competition, regulatory frameworks are shaping the market. The industry is seeing increased attention on material standards and environmental compliance. For example, the Bureau of Indian Standards (BIS) issued PPF and polymer standards, alongside UNEP PPF and polymer standards. These regulations impact market entry requirements and product specifications, particularly in regions with stringent quality controls. Companies must ensure their products comply with local and international norms to avoid barriers to trade. Our analysis includes a review of these regulatory dynamics to assist in compliance planning and risk assessment.
Demand Drivers and Application Segments
The growth of the Paint Protection Film market is propelled by diverse application areas, though the automotive sector remains the dominant force. The need to protect vehicle resale value and aesthetics in an environment of increasing traffic density and road debris is a primary driver. However, the utility of PPF extends beyond personal vehicles.
Our research explores the breadth of applications, noting that while Automotive & Transportation leads in revenue contribution, other sectors are emerging. The Electrical & Electronics sector utilizes protective films for sensitive equipment, and various Other Applications present niche opportunities. The versatility of PPF materials allows for adaptation across these verticals, provided manufacturers can tailor properties such as flexibility, adhesion, and clarity to specific use cases.
Strategic focus should be placed on understanding the specific pain points in each application segment. For automotive, it is durability and aesthetics. For electronics, it may be protection against environmental stressors without interfering with functionality. Our full report segments the market to reveal where the highest value growth opportunities lie, helping clients allocate resources efficiently.
Strategic Recommendations for 2026 Decision Makers
As we move through 2026, stakeholders in the Paint Protection Film market must adopt a proactive stance. The convergence of material innovation, competitive pressure, and regulatory changes requires a holistic view of the industry. Below are key strategic areas that our research highlights for consideration:
- Supply Chain Resilience: Given the geographic diversity of manufacturers, companies should evaluate their supply chain risks. Diversifying sources or securing long-term contracts with key TPU and polyurethane film producers can mitigate volatility.
- Technology Investment: Investing in or partnering with companies that possess advanced self-healing and hydrophobic technologies is crucial. The market is shifting towards premium solutions, and legacy products may face margin compression.
- Market Positioning: Understanding the competitive concentration helps in defining positioning. Whether aiming to compete as a premium brand like XPEL or STEK, or as a cost-effective manufacturer leveraging scale, clarity on value proposition is essential.
- Regional Compliance: Keeping abreast of standards such as those issued by BIS and UNEP is necessary for global expansion. Non-compliance can result in significant market access delays.
- Aftermarket Integration: The value of PPF is often realized through installation quality. Building strong relationships with installers or investing in training programs can enhance product reputation and reduce warranty claims.
Conclusion
The Paint Protection Film market is poised for significant growth, driven by technological advancements and a global increase in vehicle protection awareness. However, capturing this growth requires more than just general market knowledge. It demands precise insights into segmentation, competitive moves, and material trends.
PW Consulting's comprehensive report on the Paint Protection Film Market offers the depth required to navigate this complex landscape. From detailed revenue forecasts to granular analysis of key players and raw material dynamics, this research is designed to empower strategic decision-making in 2026 and beyond. The overview provided here scratches the surface of the intelligence available. To unlock the full potential of your strategy with accurate data, segmentation details, and actionable recommendations, we invite you to access the complete study.
Stay ahead of the curve by grounding your decisions in verified, in-depth industry intelligence. The future of surface protection is clear, and the opportunities for those prepared are substantial.
For detailed analysis of this topic, please visit the official page: Paint Protection Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Toothbrush Market to Hit $344.8M by 2032, 6.98% CAGR
By pmarketresearch, 2026-09-15
Navigating the Electric Toothbrush Market: Strategic Insights for 2026 and Beyond
The global oral care landscape is undergoing a profound transformation. As consumer awareness of preventive health rises and digital health ecosystems mature, the electric toothbrush has evolved from a luxury accessory into a foundational component of daily wellness routines. For executives, investors, and product strategists operating in 2026, understanding the structural shifts within this category is no longer optional. It is a prerequisite for capital allocation, portfolio optimization, and competitive positioning.
PW Consulting’s latest market research on the electric toothbrush industry delivers a comprehensive, forward-looking analysis designed specifically to inform executive decision-making. This report synthesizes historical performance, forward trajectories, competitive intelligence, and regulatory dynamics into a single strategic framework. Below, we outline the core findings and explain why this intelligence is critical for navigating the 2026-2032 horizon.
Market Evolution: From Recovery to Sustained Expansion
Over the past five years, the electric toothbrush sector has demonstrated remarkable resilience and consistent growth. Building on a solid 2020 baseline, the market has expanded steadily through 2025, with annual revenue climbing to approximately 215.0 million USD. The trajectory reflects more than pandemic-era behavioral adjustments; it signals a structural shift in how consumers approach oral hygiene. As households replace aging manual devices and upgrade to smarter, feature-rich alternatives, the category has established a durable growth engine.
Looking ahead, our forecasting models project the market to reach 234.59 million USD in 2026, accelerating toward 344.8 million USD by 2032. This expansion is underpinned by a compound annual growth rate of 6.98 percent across the forecast period. Such a rate places the category firmly in the upper tier of consumer healthcare growth segments, driven by a confluence of technological innovation, demographic tailwinds, and evolving reimbursement frameworks. Importantly, the growth is not uniform. Regional adoption curves, price-tier preferences, and application-specific demand patterns vary significantly, and capturing the right opportunity requires granular, scenario-based analysis rather than broad-brush assumptions.
Product Architecture and Application Segmentation
The electric toothbrush market is not a monolith. It is defined by distinct technological pathways, each with its own value proposition, manufacturing complexity, and consumer affinity. Sonic technology currently dominates the revenue landscape, reflecting widespread consumer preference for quiet operation, perceived gentleness, and compatibility with premium branding. Rotary systems maintain a strong foothold, particularly among users who prioritize clinical plaque removal efficacy and established brand lineage. Ultrasonic and hybrid approaches, while smaller in absolute terms, represent high-growth niches where smart connectivity and clinical validation converge.
On the application side, adult consumers continue to drive the majority of category spend, but the growth narrative is increasingly diversified. Children’s oral care represents a strategically vital segment, as early habit formation creates long-term brand loyalty and opens doors to family-oriented subscription and replacement models. The geriatric population segment, while currently smaller, is gaining strategic attention as aging demographics intersect with rising periodontal health awareness and caregiver purchasing decisions. Understanding the margin profiles, replacement cycle economics, and channel dynamics across these applications is essential for portfolio planning and go-to-market execution.
Competitive Landscape: Established Giants and Disruptive Entrants
The competitive architecture of the electric toothbrush market reflects a layered ecosystem. At the top tier, multinational healthcare and consumer goods corporations leverage decades of brand equity, clinical research, and retail distribution muscle. Royal Philips N.V. continues to lead with its Philips Sonicare portfolio, emphasizing next-generation sonic technology, pressure-sensing intelligence, and app-driven engagement. Procter & Gamble Co. maintains a formidable position through its Oral-B line, with oscillating-rotation engineering and recent iO Series introductions designed to lower the barrier for manual-to-electric switchers. Colgate-Palmolive Company reinforces its oral care dominance with oscillating-rotation electric toothbrushes that align with its broader preventive health messaging.
Beneath the incumbent layer, a dynamic set of specialists and technology-forward challengers is reshaping consumer expectations. Water Pik, Inc. has carved out a differentiated position by integrating sonic oscillation with water flossing, appealing to consumers seeking all-in-one oral hygiene solutions. Foreo has gained traction with medical-grade silicone bristle designs that emphasize gentleness and aesthetic premiumization. quip has disrupted the category through minimalist design, subscription-friendly brush pod systems, and intuitive sensor feedback. Oclean Technology Co., Ltd. is pushing the boundaries of AI coaching and smart-app integration, positioning electric brushing as a data-rich, professionally guided experience.
The supply-side landscape is equally complex. A robust network of Chinese manufacturers, including Relish Tech, Auxbon, Shenzhen Libai Technology, and several Ningbo- and Shenzhen-based OEM/ODM producers, provides the industry with scalable manufacturing capacity, compliance certifications, and customization flexibility. Their role in enabling private-label programs and rapid feature iteration underscores the importance of understanding not just end-brand competition, but the entire value chain from component sourcing to regulatory compliance.
Recent Strategic Moves and Industry Dynamics
The pace of product innovation and corporate maneuvering in 2025 and early 2026 illustrates how aggressively players are competing for share. In January 2025, Procter & Gamble Co. launched the Oral-B iO2 model, explicitly engineered to simplify the transition from manual brushing. In February 2026, quip expanded its Ultra family with the Ultra Lite Sonic Electric Toothbrush, reinforcing its focus on ease of use, pressure monitoring, and long battery life. Most recently, in March 2026, Royal Philips N.V. unveiled two new Philips Sonicare ranges, pairing next-generation sonic technology with a refreshed brand direction. These launches are not isolated product refreshes; they are strategic signals about where each company believes value will be created over the next half-decade.
Underpinning these competitive moves are structural forces that will shape profitability and market access. Electric toothbrushes are classified as Class II medical devices under FDA regulations, requiring 510(k) premarket notification clearance for U.S. market entry. Powered toothbrushes must also comply with ISO 19452:2022 performance testing standards, creating a baseline of technical rigor that raises the barrier for low-quality entrants while rewarding manufacturers with established quality systems. On the materials side, toothbrush head compliance demands adherence to biocompatibility testing and FDA 21 CFR Part 177 requirements, reinforcing the importance of supply-chain transparency and documentation.
Cost structures are equally critical for strategic planning. As of 2026, manufacturing costs for electric toothbrushes range from 6 to 11 USD per unit for entry-level models, scaling to 31 to 55 USD per unit for ultra-premium smart devices. This wide cost band directly influences pricing architecture, margin potential, and the economic viability of feature-rich versus basic offerings. At the same time, the potential expansion of FSA/HSA eligibility for oral care products, as highlighted in recent public policy discussions, could meaningfully increase consumer purchasing power and accelerate adoption in price-sensitive segments.
Strategic Implications for 2026 Decision-Makers
For executives evaluating market entry, expansion, or portfolio refresh in 2026, several strategic questions demand rigorous, data-backed answers. Where should R&D investment be directed to balance clinical credibility with consumer-desired smart features? How should pricing and channel strategy adapt to the coexistence of low-cost manufacturing ecosystems and premium brand positioning? Which regional markets offer the strongest combination of growth potential and competitive whitespace? And how should companies prepare for regulatory and reimbursement shifts that could alter demand elasticity overnight?
Electric Toothbrush Market
The answers to these questions cannot be derived from high-level market size figures alone. They require detailed segmentation analysis, margin decomposition, competitive benchmarking, and scenario modeling that accounts for regulatory, cost, and consumer behavior variables. That is precisely the intent behind this report.
What You Will Find Inside the Full Report
PW Consulting’s complete Electric Toothbrush Market research goes far beyond headline numbers. The study is structured to support actionable decision-making across product strategy, commercial planning, and risk assessment. The report includes:
- Historical market sizing and forward forecasts with transparent methodological assumptions, enabling scenario planning across base, upside, and downside trajectories.
- Deep-dive segmentation analysis across technology types, application groups, and geographic regions, with attention to adoption maturity, replacement cycles, and channel dynamics.
- Competitive profiling of leading multinational brands, specialist innovators, and manufacturing partners, including recent product launches, positioning strategies, and ecosystem partnerships.
- Regulatory and standards mapping covering FDA classification requirements, ISO testing frameworks, biocompatibility compliance, and the implications of emerging reimbursement discussions.
- Supply-side and cost-structure analysis that connects manufacturing economics to pricing strategy, margin potential, and private-label feasibility.
- Strategic recommendations for portfolio prioritization, feature investment, geographic expansion, and competitive differentiation in a market that is simultaneously consolidating and fragmenting.
Each section is designed to be immediately useful for cross-functional teams. Product leaders will find guidance on feature prioritization and technology roadmapping. Commercial teams will gain clarity on pricing architecture, channel selection, and consumer segmentation. Executives and investors will benefit from a structured view of competitive intensity, market concentration, and long-term growth sustainability.
Power Toothbrush Market
Why This Research Matters Now
The electric toothbrush market in 2026 sits at the intersection of healthcare innovation, consumer technology, and regulated product manufacturing. Growth is real, but it is unevenly distributed. The winners in the next cycle will be those who can navigate the tension between premiumization and accessibility, between clinical validation and consumer experience, and between global scale and regional specificity. They will also be the organizations that treat regulatory compliance, cost discipline, and data-driven personalization as strategic capabilities rather than operational afterthoughts.
This report provides the intelligence infrastructure needed to make those decisions with confidence. It strips away the noise, focuses on the structural drivers that will shape demand and competition through 2032, and equips leadership teams with a clear framework for action.
To access the full analysis, including detailed segmentation data, competitive benchmarking, regional outlooks, and scenario-based forecasts, visit the PW Consulting market research portal. The complete report is available now for teams ready to turn market intelligence into strategic advantage.
For detailed analysis of this topic, please visit the official page: Electric Toothbrush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Power Cords Market to Hit $6,680M by 2032, Driven by 6.2% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Power Cords and Extension Cords Market: Navigating the 2026–2032 Forecast
As global electrification accelerates, infrastructure upgrades multiply, and connected devices proliferate across every sector, the power distribution ecosystem has become a focal point for strategic procurement, manufacturing planning, and competitive positioning. The Power Cords & Extension Cords Market is no longer a commoditized afterthought; it is a dynamic, regulation-sensitive, and geographically divergent segment where supply chain resilience, material economics, and compliance agility dictate margins. PW Consulting’s latest market research delivers a comprehensive, data-anchored view of this landscape, calibrated specifically to inform enterprise decisions across the 2026–2032 horizon.
This article serves as a strategic preview of the full report. It frames the macroeconomic trajectory, outlines the analytical architecture of the study, highlights the competitive dynamics shaping the sector, and embeds the latest regulatory and raw material developments that are already influencing sourcing strategies and product roadmaps. The objective is to demonstrate the report’s decision-ready rigor while preserving the granular breakdowns, scenario modeling, and proprietary benchmarking that reside in the complete publication.
Appliance Power Cord Market
Market Trajectory and the 2026–2032 Growth Arc
The historical baseline tells a clear story of steady, compounding expansion. From 2020 through 2025, the global market scaled from approximately 3.26 billion USD to an estimated 4.40 billion USD, reflecting resilient end-user demand, sustained construction and renovation activity, and the ongoing electrification of both consumer and commercial environments. That momentum carries decisively into the forecast window: the market is projected to reach roughly 4.63 billion USD in 2026 and continue its upward path toward approximately 6.68 billion USD by 2032.
Central to this trajectory is a sustained compound annual growth rate of 6.2 percent across the forecast period. While the headline figure signals healthy expansion, the real strategic value lies in what drives it. Growth is not uniformly distributed; it is being shaped by diverging regional development cycles, application-specific procurement patterns, and a structural split between indoor deployment, outdoor resilience requirements, and heavy-duty industrial specifications. Enterprises that treat the market as a single block risk misallocating capacity, mispricing SKUs, or overlooking compliance-driven substitution trends. The full report disentangles these layers, offering a calibrated view of where volume concentrates, where margin profiles diverge, and where short-cycle demand spikes are most likely to emerge.
For CFOs and supply chain leaders, the forecast is not merely a planning number; it is a stress test for inventory architecture, vendor diversification, and capital allocation. For product managers, it frames which performance tiers and certification pathways will command premium positioning. For competitive intelligence teams, it establishes the baseline against which market share shifts, pricing pressure, and regional entry timing can be measured.
Report Architecture: From Macro Signals to Operational Playbooks
The study is engineered to move beyond descriptive sizing and into actionable strategy. It combines rigorous historical reconstruction with forward-looking scenario analysis, giving leadership teams a multi-dimensional lens on demand, supply, and regulatory risk. The report’s structure is designed for direct integration into corporate planning cycles, with sections that translate market intelligence into procurement calendars, product portfolio decisions, and geographic expansion logic.
Readers can expect detailed segmentation mapping that clarifies how volume and value split across deployment environments and end-use contexts, without reducing the market to a single average. The analysis distinguishes between indoor configurations that dominate routine consumer and commercial setups, outdoor-rated solutions that must satisfy weather, abrasion, and UV resilience requirements, and heavy-duty variants engineered for sustained industrial loads and harsher operating conditions. Each category carries distinct material specifications, testing regimes, and price elasticity characteristics, and the report maps these differences to sourcing implications and commercial positioning.
Equally critical is the regional lens. Demand is shaped by local construction rhythms, retrofit cycles, data center build-outs, healthcare facility upgrades, and the pace of electrification in both developed and emerging markets. The publication provides a structured geographic framework that helps executives prioritize distribution partnerships, assess tariff and logistics exposure, and anticipate where certification requirements will create barriers or opportunities. Rather than presenting static share snapshots, the report contextualizes regional behavior within infrastructure spending patterns, import/export flows, and local compliance timelines.
The report also embeds procurement-relevant indicators, including material price trajectories, lead-time sensitivity, and the operational impact of standards revisions. By linking market size dynamics to the cost and compliance variables that actually move margins, the study enables scenario planning that is grounded in operational reality rather than theoretical growth curves.
Competitive Landscape: Coexistence of Scale Players and Niche Specialists
The competitive structure of the power cords and extension cords market reflects a deliberate division of labor between broad-line manufacturers and application-focused specialists. The full report profiles a cross-section of companies that illustrate how different strategic postures coexist within the same industry, each capturing value through distinct combinations of geographic reach, certification depth, and product engineering.
Southwire Company LLC, headquartered in Carrollton, GA, exemplifies the integrated producer that anchors its offerings in building wire, cable, and extension cords for utility, industrial, and commercial applications. Its position underscores the importance of vertical cohesion between core wire infrastructure and downstream power delivery products. Volex plc, based in Basingstoke, Hampshire, operates as a global integrated manufacturer of power cords, plugs, connectors, and custom wiring harnesses, serving consumer, industrial, and data center uses. Its profile highlights the strategic premium associated with custom configuration capabilities and multi-market qualification portfolios.
In residential and commercial electricals, Havells Ltd and Goldmedal Electricals demonstrate how regional manufacturing strength and broad distribution networks can secure enduring share in home electricals, flexible cables, switches, and power accessories. Their presence reinforces the reality that volume-driven segments reward brand trust, retail access, and consistent compliance execution as much as technical differentiation. At the same time, specialized manufacturers such as Ningbo Biaoda Electric Co., Ltd., YFC-Boneagle Electric Co., Ltd., Kord King, Electri-Cord Manufacturing, Jiaxing Hongzhou Cable Co., Ltd., Webber Electronics, Inc., Z-Tronix Inc., and Quail Electronics, Inc. illustrate the depth of capability available for hospital-grade, medical, dental, industrial, OEM, and international configuration requirements. These players often compete on certification breadth, custom cord-set engineering, and the ability to serve demanding end-use standards rather than on undifferentiated volume alone.
Strategically, the market structure matters because it shapes sourcing flexibility. Buyers can calibrate their supplier base between scale reliability and specialized compliance, while manufacturers must decide whether to compete on breadth, on certified performance in high-stakes applications, or on speed and configuration agility. The full report examines these positioning choices in greater depth, mapping how company footprints align with the segmentation and regional dynamics that drive demand.
Power Cords & Extension Cords Market
Regulatory and Material Dynamics Reshaping Sourcing Calculus
The market’s forward path is increasingly conditioned by the interplay of standards evolution and raw material economics. Two dynamics deserve particular attention because they directly influence product design, qualification timelines, and cost structures.
On the regulatory side, the July 30, 2025 revision of UL 817 introduced new requirements for Heater-Use Power-Supply Cords, with the broader standard for Cord Sets and Power-Supply Cords having been updated on the same date. For manufacturers and specifiers, this is not a procedural footnote; it is a product definition event. Heater-related applications impose distinct thermal, loading, and safety expectations, and revisions of this nature typically trigger requalification cycles, documentation updates, and in some cases material or construction adjustments. Companies that anticipate the operational implications of UL 817 changes can shorten time-to-compliance and reduce the risk of specification rejections, while those that treat standards revision as a back-office task may face delayed launches and eroded quoting accuracy.
On the cost side, polymer pricing remains a central variable in cord and cable economics. As of April 2026, PVC pricing diverged meaningfully by geography: China PVC prices reached approximately 735.45 USD per metric ton, while U.S. PVC prices stood at about 822.45 USD per metric ton. That gap is strategically significant for any organization balancing offshore sourcing, domestic production, inventory timing, and pass-through pricing. Material volatility of this nature influences not only direct cost of goods, but also the relative attractiveness of different product tiers, the feasibility of long-term supply agreements, and the negotiation leverage between buyers and suppliers. It also interacts with certification requirements, since material substitution in response to cost pressure must still satisfy performance and safety expectations.
Together, these forces define a market environment where compliance agility and input-cost intelligence are competitive differentiators. The full report integrates these developments into the broader dynamics section, linking standards and materials to segmentation behavior, regional cost structures, and the strategic options available to both producers and procurement organizations.
Why the 2026 Decision Window Demands This Level of Intelligence
Entering 2026, enterprises face a convergence of planning imperatives that makes high-resolution market intelligence essential. Demand is expanding at a durable pace, but the composition of that demand varies by environment, application, and region. Standards are being refined in ways that affect product eligibility and qualification lead times. Material pricing is diverging across geographies, altering the economics of sourcing models that may have appeared balanced on paper. In this context, decisions made on the basis of coarse market narratives are increasingly likely to produce suboptimal capacity allocation, misaligned SKU emphasis, or unanticipated compliance exposure.
The strategic value of this study lies in its ability to convert these moving parts into a coherent decision framework. It helps leadership teams answer practical questions: where should inventory and production emphasis be placed to match the most resilient demand pools; which product categories carry the strongest combination of volume and margin durability; how should supplier portfolios be structured to absorb material volatility and certification cycles; and where do regional dynamics create entry timing advantages or risks. By anchoring these questions in a 2026–2032 horizon, the report enables plans that are forward-compatible rather than reactive.
For organizations that compete on reliability, certified performance, or configuration agility, the publication also serves as a benchmarking foundation. Understanding how market size, segmentation behavior, and competitive positioning interlock makes it possible to calibrate go-to-market priorities, refine pricing strategy, and anticipate where differentiation will command premium attention in specification processes.
What the Complete Study Unlocks
This preview has outlined the structural logic of the market, the trajectory implied by the historical and forecast data, the competitive architecture that defines how value is captured, and the regulatory and material variables that are already reshaping operational calculus. The full report extends well beyond this frame. It delivers the detailed segmentation analysis, regional demand context, company profiling depth, standards impact assessment, and material-cost sensitivity perspective needed to translate macro direction into executable plans.
Because the study is designed to support real-world decision cycles, the complete version includes the granular breakdowns, scenario considerations, and benchmarking references that leadership teams require when setting procurement calendars, prioritizing product development, evaluating distribution geography, and stress-testing sourcing strategies against regulatory and input-cost shifts. These elements are intentionally developed in full within the publication so that readers can apply them directly to internal planning without having to reconstruct the underlying logic.
For executives, analysts, and operations leaders who need to align strategy with the realities of a growing but increasingly complex market, the complete research offers the evidentiary base and structural clarity required to move from awareness to action. To access the full segmentation detail, competitive profiles, regional context, and compliance and materials analysis, and to integrate the complete forecast with your internal planning models, visit the source page for the Power Cords & Extension Cords Market research and obtain the full report.
For detailed analysis of this topic, please visit the official page: Power Cords & Extension Cords Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Fiber Cement Market Hits $22.45 Billion in 2025, 4.08% CAGR Forecast to 2032
By pmarketresearch, 2026-09-15
The Fiber Cement Market in 2026 A Strategic Crossroads for Construction and Manufacturing Leaders
The global fiber cement market stands at a decisive inflection point as it moves through the 2026-2032 forecast horizon. An economy that reached 22.45 billion USD in 2025 is not merely expanding; it is restructuring around material innovation, regulatory realignment, and shifting end-use expectations. For executives, procurement leaders, and investors, the question is no longer whether fiber cement will grow, but how capital, capacity, and competitive positioning should be allocated to capture durable advantage. Our latest Fiber Cement Market study translates these macro trajectories into an actionable decision framework, giving leadership teams the precision they need to plan capacity, pricing, distribution, and product architecture through the end of the decade.
This research is built for those who must act, not merely observe. The analysis spans historical performance from 2020 to 2025, establishes a 2025 base year, and projects forward to 2032 with disciplined scenario logic. Total revenue is tracked in USD across a billion-unit scale, reflecting a maturation pathway that moves from 22.59 billion USD in 2026 toward 29.71 billion USD in 2032. That trajectory implies a compound annual growth rate of 4.08 percent, a pace that signals sustained demand while simultaneously exposing the operational friction points that can erode margin if left unmanaged. The study treats this growth as a strategic asset and a risk surface, mapping both the upside and the pressure points that will shape enterprise outcomes over the next seven years.
What makes this intelligence especially valuable in 2026 is its timing. The industry is navigating a convergence of forces that will test supply chain resilience, cost discipline, and product differentiation at the same time. Raw material price volatility for cement and cellulose is reshaping input economics, while labor cost escalation in high-cost states continues to push up total project cost for siding and exterior applications. At the same time, regulatory attention is intensifying, with the United States Environmental Protection Agency issuing guidance on safe use and exposure to fibrous silicate minerals in manufacturing, and the government of British Columbia proposing additional safety measures for fibrous silicate minerals in plants. These developments are not peripheral news; they alter compliance costs, operational standards, and the speed at which new capacity can be brought online. The report integrates these realities into a single operational lens so that leaders can forecast not just demand, but the true cost and feasibility of serving that demand.
Why This Study Matters for 2026 Enterprise Decisions
Strategic planning in 2026 requires more than a top-line growth assumption. It requires a granular view of where value is created and where it leaks. The market’s structure is concentrated enough to reward scale, yet dynamic enough to open opportunities for disciplined regional and product plays. With the top three competitors accounting for 60.0 percent of market share and the top five reaching 70.0 percent, the competitive field is clearly tiered. That concentration changes the logic of entry, expansion, and defense. Organizations must understand which segments carry the greatest margin potential, which geographies offer the most efficient route to volume, and which product forms align with emerging specification trends. This report is designed to answer those questions with a level of clarity that supports capital deployment and go-to-market strategy, without forcing leaders to guess at the underlying segmentation logic.
The study is also timed to support decisions that depend on near-term visibility. Forecasts begin at 22.59 billion USD in 2026 and step upward through 24.18 billion USD in 2027, 24.52 billion USD in 2028, 25.83 billion USD in 2029, and 27.95 billion USD in 2030, before reaching an end-of-horizon range that closes at 29.24 billion USD in 2031 and 29.71 billion USD in 2032. These figures are not presented as abstract numbers. They are used to anchor scenario planning, identify when demand intensifies, and highlight the intervals in which competitors are most likely to adjust capacity, pricing, or distribution. For a procurement director monitoring cellulose and cement cost exposure, that cadence matters. For a regional business unit evaluating whether to expand distribution, it matters even more.
Inside the Report Architecture and Practical Utility
The study is organized to move from market structure to execution, ensuring that insights can be operationalized rather than simply read. It examines the market through multiple lenses, including type, application, and region, so that users can map growth into the specific business lines and territories that matter most to their organization. The type view addresses the product architecture that defines sourcing, formulation, and differentiation strategies. The application view connects demand to functional use cases in siding, roofing, molding and trim, flooring, and other end markets, helping teams understand where specification momentum and replacement cycles are likely to shape volume. The regional view supports distribution planning, plant siting logic, and competitive targeting by showing where demand is accumulating and where saturation or cost pressure may alter the route to profit.
Beyond segmentation, the report translates market structure into competitive strategy. It profiles the organizations that are defining the pace of the industry, from established building-product leaders to regional specialists with strong local execution. The analysis does not stop at corporate description. It examines how each player’s product focus, manufacturing footprint, and market posture position them for the next phase of growth, and it identifies where concentration creates either a defensive moat or an incentive for disruption. This company-level intelligence is especially useful for teams evaluating partnership opportunities, competitive threats, or potential acquisition targets, because it relates each organization’s specific offerings to the larger demand architecture.
The study also integrates a forward-looking set of industry developments that carry direct operational implications. Recent activity shows how fast the competitive and standards environment can change. In February 2025, James Hardie Building Products Inc. unveiled new and expanded Hardie products, including Artisan Trim, at the NAHB International Builders Show, signaling continued product-line broadening in response to specification opportunities. In May 2025, the company announced a three-year exclusive distribution agreement with Davidson Homes for Hardie siding and trim products, an example of how channel control and builder relationships are becoming central to share defense and growth. Later, in October 2025, ICC-ES proposed new criteria for fibre-cement siding complying with ASTM C1186 or ISO 8336 in combustible and noncombustible construction, an indication that the regulatory and testing environment is tightening around material performance and application rules. Each of these events is treated as a strategic signal, not just an industry headline, and the report explains what they imply for product roadmaps, channel strategy, and compliance readiness.
Equally important, the report provides a practical view of the cost and risk environment. It addresses raw material price fluctuations for cement and cellulose that raise production costs, and it places those pressures within the broader context of labor and total project economics. It also reflects the regulatory landscape shaping manufacturing operations, including EPA guidance on safe use and exposure to fibrous silicate minerals and British Columbia’s proposed additional safety measures for plants. These inputs are woven into the analysis so that readers can assess the full stack of operational constraints, from input procurement to worker safety, compliance documentation, and final installed cost. For organizations that must justify capital expenditure or renegotiate supply terms, that integrated view is what turns information into decision support.
Competitive Positioning and the Shape of Industry Leadership
The competitive map in this study is built to show where advantage is durable and where it is contestable. The market’s concentration profile means that a limited number of firms hold substantial influence over pricing expectations, specification penetration, and channel relationships. At the same time, the breadth of profiled organizations indicates that leadership is not monolithic. Different companies compete through different product forms, end-use strengths, and regional reach, which creates a market in which specialization can still outperform undifferentiated scale in the right context.
James Hardie Industries PLC, headquartered in Ireland, continues to anchor the market with a focused offering built around Hardie fiber cement siding and backer boards. Its recent product unveiling and exclusive distribution agreement underscore a strategy that combines product expansion with channel exclusivity, reinforcing brand preference and builder-level pull. ETEX Group, based in Belgium, competes with fiber cement boards and sheets, positioning around building-envelope and construction use cases where board performance and consistency matter. Saint-Gobain, headquartered in France, brings a wider construction-products footprint and offers fiber cement products for construction applications, leveraging scale and technical breadth across multiple building systems. Nichiha Corporation, based in Japan, emphasizes high-performance fiber cement panels and siding, aligning with markets that value precise engineering and exterior durability. Cembrit Holding A/S, from Denmark, focuses on fiber cement siding and exterior products, supporting architectural and weather-exposed applications where finish and long-term performance drive specification decisions.
Fiber Cement Market
Regional specialists and application-focused players round out the competitive landscape and add important nuance to market strategy. Allura USA operates in the United States with fiber cement siding products, while American Fiber Cement Corporation provides boards and sheets for construction-related demand. Elementia Materials contributes fiber cement products for construction from Mexico, and Everest Industries Limited supports board demand from India. CSR Limited extends fiber cement products from Australia, and Plycem Corporation competes in the U.S. market with siding and boards. Swisspearl Group, headquartered in Switzerland, emphasizes fiber cement cladding and siding, aligning with architectural exterior solutions. Together, these organizations illustrate that the market is not only contested by global leaders but also shaped by companies that win through regional density, product specificity, or cost-efficient manufacturing.
This diversity is strategically meaningful. For an incumbent, it highlights the need to protect specification share, strengthen distribution agreements, and reduce exposure to input and compliance cost shocks. For a challenger or regional operator, it suggests that targeted product forms, localized service, and selective channel partnerships can create defensible positions even in a concentrated market. The study connects these competitive realities to the segmentation logic described earlier, allowing readers to see where each company’s strengths intersect with demand pools and where gaps may open for new investment or partnership.
Strategic Implications for Capital, Supply Chain, and Growth Planning
The most valuable use of this research is to convert market direction into internal priorities. In a market projected to expand from 22.59 billion USD in 2026 to 29.71 billion USD in 2032, the organizations that outperform will be those that treat growth as a systems problem. They will align product architecture with specification momentum, build supply chains that can absorb raw material volatility without eroding margin, and prepare for regulatory change as part of operational planning rather than as an afterthought. They will also recognize that construction-sector demand is increasingly shaped by project economics, including labor and material cost dynamics in high-cost regions, which can alter both replacement cycles and new-build adoption.
Because the report keeps its most precise segmentation detail and company-level scenario data inside the full publication, it preserves the analytical tension that makes the study useful. Leaders can see the shape of the market, understand the forces moving it, and identify where strategic action matters most, while reserving the deeper quantitative detail for the moment they are ready to commit capital or revise a commercial plan. That structure is intentional. It allows executives to build confidence in the research rigor and then retrieve the specific numbers, split data, and playbook-level recommendations that support board-level decisions.
Fiber Cement Board Market
For 2026, the strategic takeaway is straightforward. Fiber cement is expanding within a market that is large enough to matter and structured enough to reward disciplined strategy. The firms that will benefit most are those that can read the market not just as a growth curve, but as a map of concentration, regulation, input risk, product form, and application demand. This report provides that map. It gives decision-makers the context to see where the market is heading, the competitive logic to understand who is gaining ground, and the operational grounding to act with confidence.
The full study goes further by delivering the detailed segmentation, regional and application-level revenue context, and company-specific strategic readouts that support precise planning. Those elements are where the research moves from directional insight to executable intelligence. Readers looking to lock in capacity strategy, refine pricing models, prioritize channels, or evaluate competitive exposure will find the complete dataset and scenario framework essential. For teams preparing for the 2026-2032 window, this publication offers both the high-level view needed to set direction and the deeper market intelligence required to execute it.
For detailed analysis of this topic, please visit the official page: Fiber Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com